US Business News

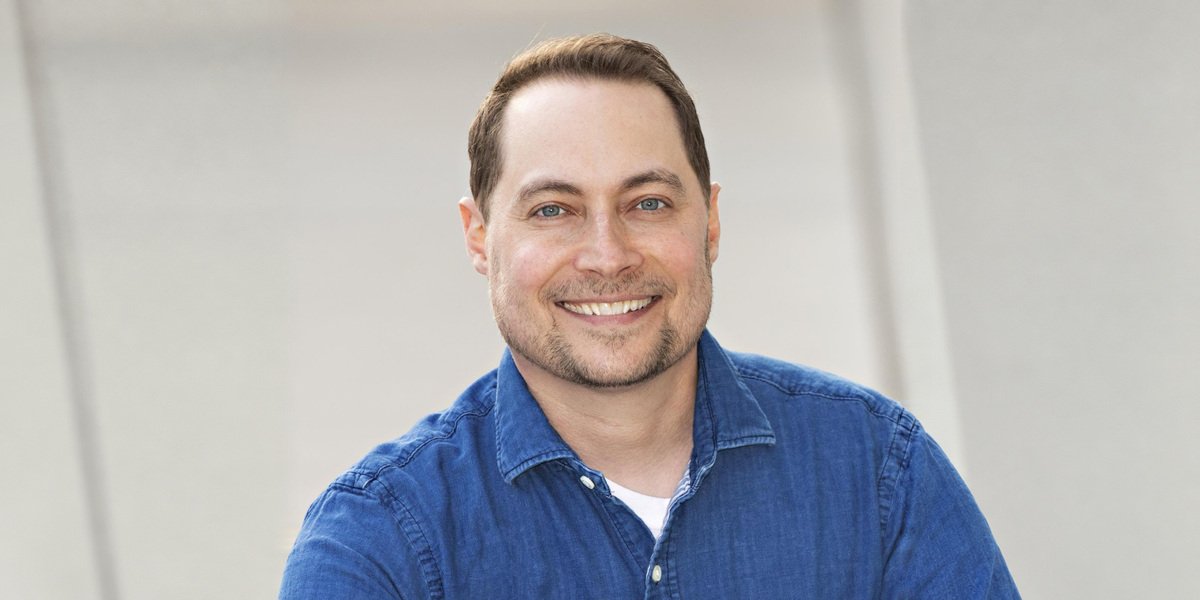
Dave Labowitz Says Your Business Coach Might Be a Life Coach
By: Curious Fortune Media

Coaching keeps growing. The International Coaching Federation’s 2025 Global Coaching Study counted 122,974 coach practitioners worldwide and estimated annual industry revenue at $5.34 billion, up 17% from 2023.

That continual expansion makes sense in a field where almost anyone can print “business coach” on a card. Dave Labowitz, a business coach who spent years as an executive in venture-backed startups, describes coaching as an industry with zero regulation, and he draws a firm line through the middle of it. “There are a lot of people who call themselves business coaches, but they’re really only skilled to be life coaches for business people. They might be great at mindset work and facilitation, but if they don’t have the business chops to help your business grow, then they’re not truly business coaches,” says Labowitz. In his view, business coaching should start with the business itself: sales, marketing, operations, finance, and product, with mindset work handled as it comes up rather than as the opening move.

Two Skill Sets, One Order of Operations

Labowitz breaks business coaching into two skill sets: experience building businesses, and the facilitation of personal development. Both matter. The question is which one leads.

Instead of leading with soft skills, Labowitz leads with strategy and tactics, and addresses personal growth issues when they surface in the course of that work. The result is roughly an 80/20 blend of brass tacks to soft skills.

“If a founder’s problem is cash flow or a stalled sales pipeline, starting with how they feel about it doesn’t fix it,” Labowitz says. “We work the business problem first. The mindset work still happens, but it shows up when it’s actually holding you back, and then it’s much easier to see where the opportunity is for change.”

His clients range from founders who need help knowing what they don’t know to experienced leaders who want to be pushed out of their comfort zone or need a senior-level confidant for strategy. Their companies run from pre-revenue to $350 million, and include bootstrapped startups, venture-backed companies, and larger private-equity-owned businesses, along with solopreneurs, and the occasional actor or rock star.

The CEO Hat

A core method he teaches comes from the Monday mornings of his startup years. Each week, the CEO brought the executive team into a room. Every executive reported on their department, asked for the support they needed from the other departments or the CEO, and left with a cohesive plan for the week ahead.

Labowitz coaches clients to run their businesses the same way, whether or not they have an executive team. He calls it putting on the CEO Hat: thinking like a CEO, then working through strategy and tactics for each of the five departments every business has, which he defines as sales, marketing, operations, finance, and product management or engineering. A solo founder holds the meeting with themselves, one department at a time. This approach is designed to keep all parts of the business moving forward together.

An Unconventional Route to the Corner Office

Labowitz did not take the expected path to the boardroom. He dropped out of high school at the beginning of 10th grade, earned a GED, and won his diploma in a bet with the school district. After a semester of community college with a 4.0, he transferred to a four-year college and graduated magna cum laude with a BA in psychology.

He worked briefly as a software and database engineer before falling for startups, then earned his MBA in 2006 from Pepperdine’s Graziadio Business School. His executive career in venture-backed startups spanned four companies, three of which ended in exits. In 2016, he retired from that career and transitioned into coaching.

“I loved building companies, but the startup hours could be brutal,” Labowitz admits. “Coaching let me cut back on the 70-hour weeks while keeping the part I enjoyed most, which was watching people learn, grow, and get it right.”

Deep Impact Over Wide Reach

His online course, “Essential Lessons for First-Time Managers,” has been taken by hundreds of thousands of people worldwide and is required training by the Philippines Department of Education for all school principals and head teachers. His coaching practice, by contrast, stays deliberately small.

Labowitz does little to nothing on social media, which he sees as overwhelmed with AI-generated content, and he does not need it. His work comes through long-term clients, referrals, and SEO. He would rather have a deep impact on a few clients than a minor impact on a wide audience.

That choice fits his style and values. In an industry growing as quickly as coaching, he is betting the clients who matter most are not looking for the loudest coach, but for someone who has sat in the Monday meeting, knows what each department should be reporting, and can tell them which number to fix first.
Visionary Book Publishers Book Marketing Services for Your Launch

By: Jay Kt

Launch week is one of the most exciting moments in an author’s journey, and one of the most important for visibility. A well-planned launch concentrates attention, builds momentum and gives your book its best chance to connect with readers early. But launches do not succeed by accident. They require preparation that begins weeks or even months before release day. At Visionary Book Publishers, we help authors plan and execute effective book launch marketing as part of our book marketing services. Use this step-by-step checklist to prepare your own launch.

Three to Six Months Before Launch

Step 1: Define Your Author Branding

Author branding is the consistent identity readers associate with you: your genre, your voice, your visual style and your values. Before marketing a specific book, clarify how you want readers to perceive you as an author.

Consider your author name presentation, professional photos, a short bio, brand colors and fonts that complement your covers, and the tone you use in posts and newsletters. Strong author branding makes your marketing recognizable and helps readers remember you across platforms and books.

Step 2: Build or Refresh Your Author Website

Your website is your launch headquarters. Make sure it includes an updated home page, a dedicated book page or landing page, your bio, a newsletter sign-up and links to your social media. When readers hear about your book, your website should give them everything they need.

Step 3: Start Growing Your Email List

An email list lets you reach interested readers directly on launch day. Offer a reason to subscribe, such as a free chapter, short story or behind-the-scenes updates, and promote the sign-up across your channels.

Step 4: Finalize Your Book Description and Metadata

Your book description is one of your most important marketing tools. It should hook readers, convey genre and tone and end with a reason to buy. At the same time, choose accurate categories and relevant keywords so readers can find your book in retailer searches.

One to Three Months Before Launch

Step 5: Plan Your Amazon Book Marketing

For many independent authors, Amazon is a major retail channel, so Amazon book marketing deserves careful attention. Key elements include an optimized product page with a compelling description, accurate categories, relevant keywords, an author profile and, where appropriate, enhanced content features available to authors.

Some authors also use advertising on the platform to reach readers browsing similar books. Amazon book marketing works best when your listing is fully optimized before you send traffic to it. Visionary Book Publishers is not affiliated with Amazon, but we stay informed about its published guidelines and help authors prepare listings that follow them. Authors should always keep control of their own accounts and never share passwords or verification codes.

Step 6: Arrange Early Reviews

Reviews help readers decide whether to try a new book. Ethical approaches include sharing advance copies with readers, bloggers and reviewers who may choose to leave honest reviews. Avoid any practice that involves paying for reviews or requiring positive ratings, as these can violate retailer policies.

Step 7: Prepare Marketing Assets

Create the materials you will use throughout the launch: social media graphics, quote cards, a book trailer if desired, an announcement email and press materials. Consistent visuals reinforce your author branding and make your launch look professional.

Step 8: Plan Media and Outreach

Identify podcasts, blogs, local media and community organizations that reach your target readers. Prepare pitches that explain why your book or story is relevant to their audience. Outreach takes time, so start early.

Launch Week

Step 9: Announce Your Book Everywhere

On launch day, share the news with your email list, social media followers, website visitors, friends, family and professional network. Make it easy for supporters to share your announcement.

Step 10: Concentrate Your Activity

Book launch marketing is most effective when activity is concentrated. Schedule posts, emails, interviews, events and any advertising campaigns to support each other during launch week. Engage with readers who comment, share or post about your book.

After Launch

Step 11: Keep the Momentum Going

Many books find readers gradually, so marketing should continue after launch week. Share reader reviews, behind-the-scenes content and related articles. Consider seasonal promotions, events and ongoing advertising.

Step 12: Measure and Adjust

Review what worked: which channels drove traffic, which posts resonated and which outreach led to opportunities. Use these insights to refine your ongoing marketing and plan future launches.

Common Launch Mistakes to Avoid

Even well-prepared authors can stumble during a launch. One frequent mistake is starting promotion only on release day, leaving no time to build anticipation. Another is sending readers to a retailer page with an incomplete description or missing categories. Some authors spread their efforts across too many platforms and engage meaningfully with none. Others stop promoting entirely once launch week ends. Successful book launch marketing avoids these traps by starting early, preparing every listing in advance, focusing on the channels where readers are most active and planning post-launch activity before release day arrives.

A Note on Expectations

A strong launch improves your book’s visibility and gives it a solid start, but no one can guarantee specific sales figures or rankings. Readers, retailers and market conditions all play a role. Focus on what you can control: a professional book, a clear plan and consistent, ethical promotion.

How Visionary Book Publishers Can Help

Our team can support every stage of this checklist, from author branding and website design to Amazon book marketing preparation, content creation and outreach. We begin with a conversation about your goals and provide a written proposal outlining services, timelines, fees and any separate campaign costs.

Launch Your Book with Confidence

A successful launch is built on preparation, consistency and a clear plan. With thoughtful book launch marketing, your book can enter the world with the attention it deserves. Prepare your launch hub with our author web design services, or contact Visionary Book Publishers to start planning your launch today.

Mastercard Revenue Growth Hits 14% as U.S. Credit Outpaces Debit

Mastercard revenue growth reached 14% in the third quarter of 2026, supported by higher payment activity and expanding services revenue. U.S. credit purchases increased faster than debit purchases, although a major card-network migration affected the comparison. The results reveal differences in American spending activity alongside Mastercard’s higher quarterly earnings.

Key Takeaways

  • Mastercard reported $9.8 billion in third-quarter revenue, up 14% year over year, while net income increased 18%
  • U.S. purchase volume rose 6.7% to $803 billion, while the number of transactions increased 3.5%
  • Credit and charge purchase volume grew 10%, compared with 2.8% growth for debit
  • Value-added services revenue increased 19%, contributing to Mastercard’s overall earnings growth

Mastercard reported higher quarterly revenue and profits on Thursday, October 29, 2026, as increased payment activity supported its financial performance. The Purchase, New York-based company recorded $9.81 billion in net revenue for the three months ended September 30, compared with $8.60 billion during the same period in 2025.

The results exceeded analysts’ expectations and highlighted differences in U.S. card spending. Credit and charge purchase volume grew considerably faster than debit activity, while the total value of transactions increased at a higher rate than the number of purchases recorded.

Mastercard Revenue Growth Exceeds Wall Street Expectations

Mastercard’s third-quarter revenue surpassed the approximately $9.66 billion expected by analysts surveyed by FactSet. Adjusted earnings reached $5.31 per share, exceeding the consensus estimate of $5.17.

Net income increased 18% to $4.63 billion from $3.93 billion a year earlier, while diluted earnings per share rose to $5.28 from $4.34.

Higher payment activity contributed to the results. Mastercard reported approximately $3 trillion in worldwide gross dollar volume, an increase of 7% on a local-currency basis. Global purchase volume rose nearly 9%, while cross-border payment volume increased 11%, reflecting higher spending activity involving cardholders and merchants in different countries.

In the United States, purchase volume on Mastercard-branded credit, charge and debit programs reached $803 billion during the quarter, up 6.7% year over year. The company recorded nearly 12 billion domestic purchase transactions, representing a smaller increase of 3.5%.

The difference indicates that the average dollar value of transactions increased, although the figures do not establish whether higher prices or changes in purchasing patterns accounted for that movement.

The results also differ from broader U.S. retail spending trends. Retail and food-service sales declined 0.6% in July, according to Census Bureau data, while Mastercard’s quarterly figures reflected higher purchase volume across its payment network. The two measures cover different periods and payment activity.

U.S. Credit Purchases Rise 10% as Debit Growth Slows

Mastercard’s domestic operating figures showed that credit and charge purchase volume increased 10% to $455 billion during the third quarter. The number of transactions on those programs rose 9.1% to approximately 4.88 billion, indicating growth in both transaction frequency and total purchase value.

Debit activity increased at a slower rate. U.S. debit purchase volume reached $348 billion, up 2.8% from a year earlier, while the number of debit purchase transactions declined 0.1% to approximately 7.11 billion.

Although debit accounted for more transactions, credit and charge programs generated greater total purchase value.

The difference was also evident in year-over-year comparisons. During the third quarter of 2025, Mastercard reported 6.7% growth in U.S. credit and charge purchase volume and 7.5% growth in debit purchase volume. The latest figures therefore show faster credit growth alongside slower reported debit growth.

However, the comparison reflects more than consumer purchasing decisions.

During Mastercard’s October 29 earnings presentation, the company identified Capital One’s debit-card migration as a factor affecting U.S. debit gross dollar volume growth. The migration began near the end of the third quarter of 2025 and continued into early 2026, influencing the network’s reported activity.

That qualification matters when assessing the difference between credit and debit spending. Mastercard’s figures confirm faster growth in reported credit purchases, but they do not independently establish that American households broadly increased borrowing or shifted their preferred payment methods.

Consumer sentiment data also provide a separate perspective. The August U.S. consumer confidence reading declined to 89.4 from 90.2 in July, reflecting weaker short-term expectations among surveyed households. That measure captures consumer sentiment rather than actual transactions, making it distinct from Mastercard’s quarterly payment figures.

Services Revenue Climbs 19% as Mastercard Reports Higher Profits

Mastercard’s earnings growth extended beyond card purchase activity. Payment-network net revenue increased 11% year over year, supported by higher transaction volumes, cross-border activity and pricing.

Meanwhile, revenue from value-added services and solutions rose 19%. The segment includes fraud prevention, data analytics and other services related to payment security and business operations.

These operations contributed to Mastercard’s overall revenue increase alongside its core payment-network business. Customer rebates and incentives within the payment-network division also increased 18%, reflecting higher business activity and new or renewed agreements.

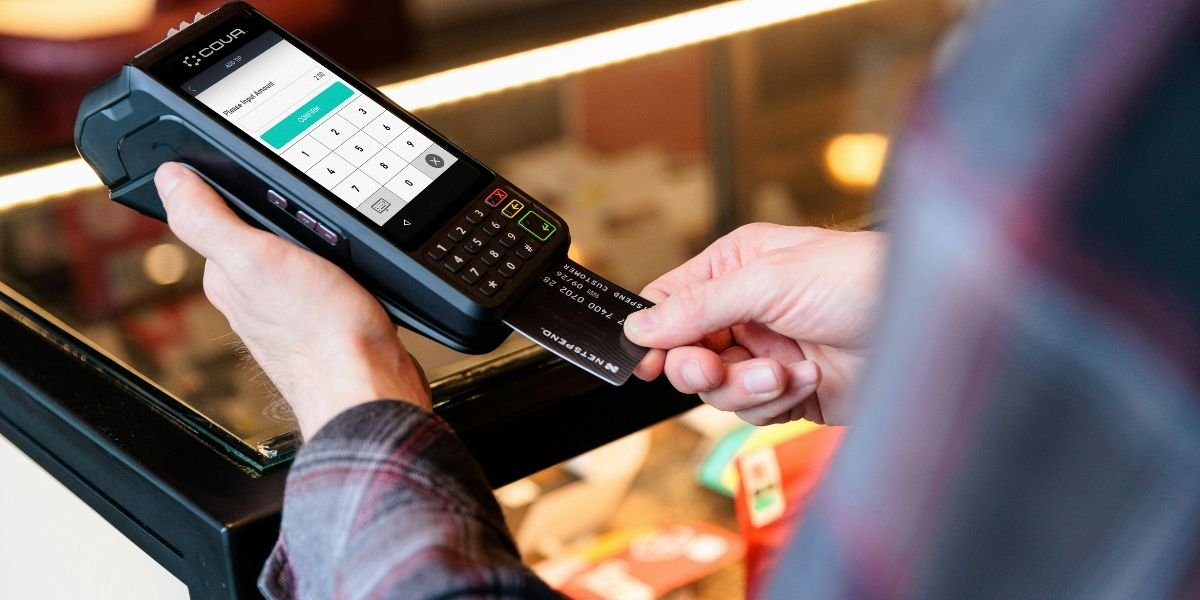
Mastercard Revenue Growth Hits 14% as U.S. Credit Outpaces Debit

Photo Credit: Unsplash.com

Operating income reached approximately $5.9 billion, a 16% increase from the corresponding quarter in 2025. Operating expenses rose 11% to about $3.9 billion, allowing the company’s reported operating margin to improve to 59.8% from 58.8%. Its adjusted operating margin reached 60.5%, compared with 59.8% a year earlier.

The quarterly performance was consistent with higher revenue across the first nine months of 2026. Mastercard reported approximately $27.5 billion in worldwide net revenue during that period, representing 15% growth from the comparable period in 2025.

U.S. purchase volume reached $2.329 trillion during the first nine months, up 6.1%, while domestic purchase transactions increased 3.3% to 34.62 billion.

Over the same period, U.S. credit and charge purchase volume increased 9.3%, compared with 2.3% growth for debit. The figures show faster reported credit purchase growth across the year to date, alongside the network-related factors affecting debit comparisons.

Frequently Asked Questions

How much did Mastercard’s revenue grow in Q3 2026?

Mastercard revenue growth reached 14% in the third quarter of 2026, bringing net revenue to approximately $9.8 billion. Net income increased 18% to $4.63 billion, while adjusted earnings reached $5.31 per share.

How much did U.S. Mastercard card spending increase?

U.S. purchase volume on Mastercard-branded programs increased 6.7% to $803 billion during the quarter. The company recorded nearly 12 billion domestic purchase transactions, representing 3.5% year-over-year growth.

Why did Mastercard’s credit purchases grow faster than debit?

Mastercard reported 10% growth in U.S. credit and charge purchase volume, compared with 2.8% growth in debit purchase volume. Capital One’s debit-card migration affected reported debit comparisons, so the difference cannot be attributed solely to changes in consumer payment preferences.

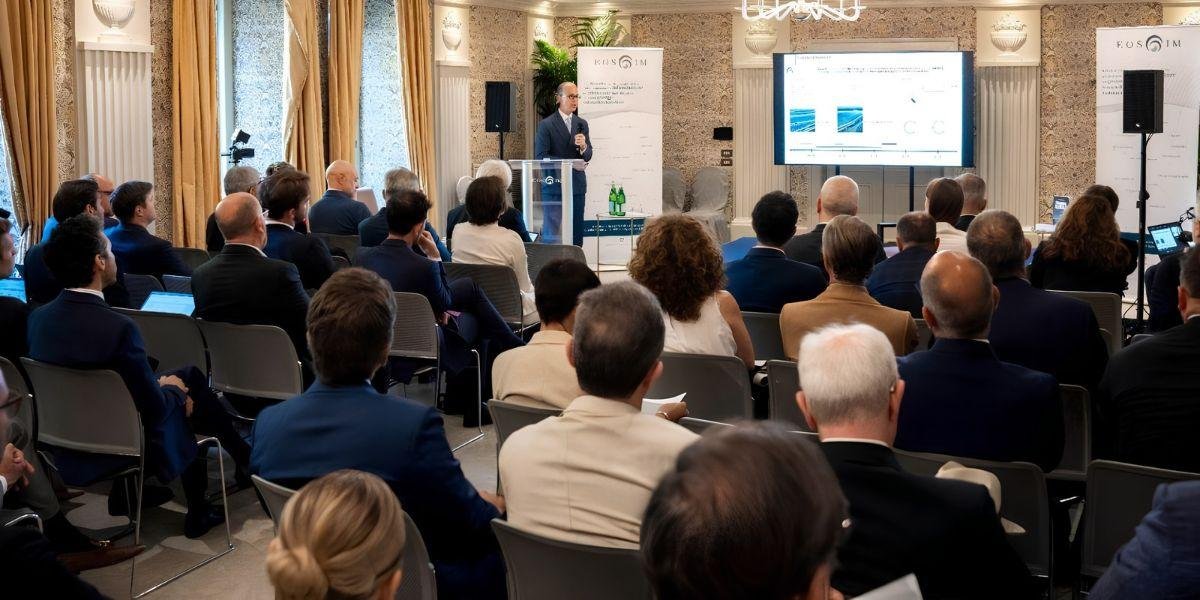
Giuseppe La Loggia and the Development of Clean Energy Infrastructure Strategy at EOS Investment Management

Renewable energy has moved from the margins of European policy to the centre of its economic architecture. The European Green Deal and the “Fit for 55” legislative package have embedded into law the commitment to reduce greenhouse gas emissions by at least 55 per cent by 2030 compared with 1990 levels. Energy security concerns, amplified by geopolitical instability and wholesale price volatility, have reinforced the strategic case for domestic generation and electrification. The pace of deployment reflects this shift: Europe added more than 56 gigawatts of new solar capacity in 2023 alone, confirming that renewables have matured into a mainstream infrastructure asset class capable of absorbing significant institutional capital.

It was in this context that Giuseppe La Loggia joined EOS Investment Management Group in December 2018 as Senior Partner, assuming responsibility for leading the Clean Energy Infrastructure division. Based in London, where EOS IM operates its FCA-authorised investment management platform, he was tasked with repositioning the firm’s sustainable infrastructure strategy towards large-scale, unsubsidised renewable energy assets. The focus was on Southern Europe, primarily Italy and Spain, markets that combine strong resource fundamentals with evolving regulatory frameworks and growing demand for privately financed energy transition projects.

The launch and scaling of the EOS Renewable Infrastructure Fund II provided the institutional foundation for this strategy. Structured as a Luxembourg RAIF, the fund closed at approximately €293 million, exceeding its original €250 million target and attracting a diversified investor base spanning pension funds, banks, insurers, and family offices. Its distinguishing feature was a greenfield, grid-parity orientation: rather than relying solely on legacy feed-in tariffs, the fund targeted utility-scale solar projects capable of operating on merchant economics or under private power purchase agreements. Execution depended on rigorous site selection, permitting discipline, construction oversight, and careful capital structuring to ensure bankability.

By 2021 and 2022, this strategy translated into tangible projects. In Lazio, EOS IM, together with Capital Dynamics, acquired the rights to develop one of the largest unsubsidised solar clusters in central Italy, comprising three photovoltaic sites with a combined capacity of approximately 87 megawatts. The programme advanced into construction with long-term green financing from leading European banks, supported by SACE’s Green Guarantee scheme. The transaction demonstrated that unsubsidised Italian solar projects could attract institutional-grade debt with extended tenors, marking an important milestone in the evolution of grid-parity infrastructure finance in the country.

Parallel expansion took place in Sardinia and other southern regions. In 2023, EOS IM completed the acquisition of a 42-megawatt unsubsidised photovoltaic plant in Sardinia, one of the island’s larger grid-parity solar assets. Designed to generate more than 80 gigawatt-hours annually, sufficient to power tens of thousands of households, the project was structured with provisions for future battery storage integration, reflecting a forward-looking approach to grid stability and operational optimisation. By that stage, the Fund’s Italian portfolio included a combination of operational plants, construction-stage assets, and advanced development projects, creating a scalable cluster model rather than isolated installations.

Further acquisitions in Lazio deepened EOS IM’s footprint, expanding the pipeline of permitted and late-stage development projects and reinforcing its presence in central Italy. The emphasis was not solely on capacity growth, but on assembling geographically coherent portfolios that could benefit from shared infrastructure, streamlined permitting management, and coordinated construction oversight. Financing structures ranged from project-level green loans to cross-border facilities at the holding level, illustrating how private equity capital, commercial bank debt, and public credit support mechanisms could be integrated to lower the cost of capital and enhance resilience.

It was on this established base that EOS IM agreed to acquire a 294-megawatt Italian solar portfolio from Lightsource bp, comprising projects that are permitted or in advanced stages of development. Market commentary described the transaction as one of the more significant renewable deals completed in Italy at the time. The acquisition materially expanded the platform’s construction-ready capacity. It underscored its ability to convert the development pipeline into bankable, scalable assets.

Concurrently, EOS IM entered the Spanish market by integrating operating photovoltaic plants under long-term power purchase agreements. This move introduced geographic diversification and complemented merchant exposure in Italy with contracted revenue streams, strengthening the overall portfolio’s risk profile. The deliberate combination of development upside, stabilised assets, and diversified revenue mechanisms reflected a mature infrastructure investment philosophy.

Throughout this period, financial structuring remained central to execution. Green loans, project finance facilities, and institutional capital structures were employed not as ancillary features but as core strategic tools. Environmental and social considerations were incorporated into investment criteria, particularly in agricultural regions where land use and community impact required careful engagement. Portfolio construction, therefore, operated at the intersection of regulatory compliance, carbon-reduction objectives, and risk-adjusted return thresholds.

Since 2018, EOS IM’s Sustainable Infrastructure Investment strategy under La Loggia’s leadership has mirrored the broader transformation of European renewable infrastructure finance. What was once viewed solely as policy-dependent has evolved into a sector defined by disciplined underwriting, sophisticated investment strategy, project contract structuring, portfolio strategies, and increasingly sophisticated capital structures. The platform’s growth illustrates how private capital can align with national decarbonisation agendas while delivering institutional-grade returns. In tracing this phase of his career, La Loggia’s professional trajectory reflects not only the expansion of a firm but also the consolidation of renewable energy at the heart of Europe’s economic and financial strategy.

Disclaimer: This article is for general informational purposes only. The information presented is based on publicly available sources and is not intended to constitute professional, financial, legal, or investment advice. Readers are encouraged to conduct their own research and seek professional guidance where appropriate.