US Business News

How Christopher Mackin Builds Wealth With Purpose
By: William Jones

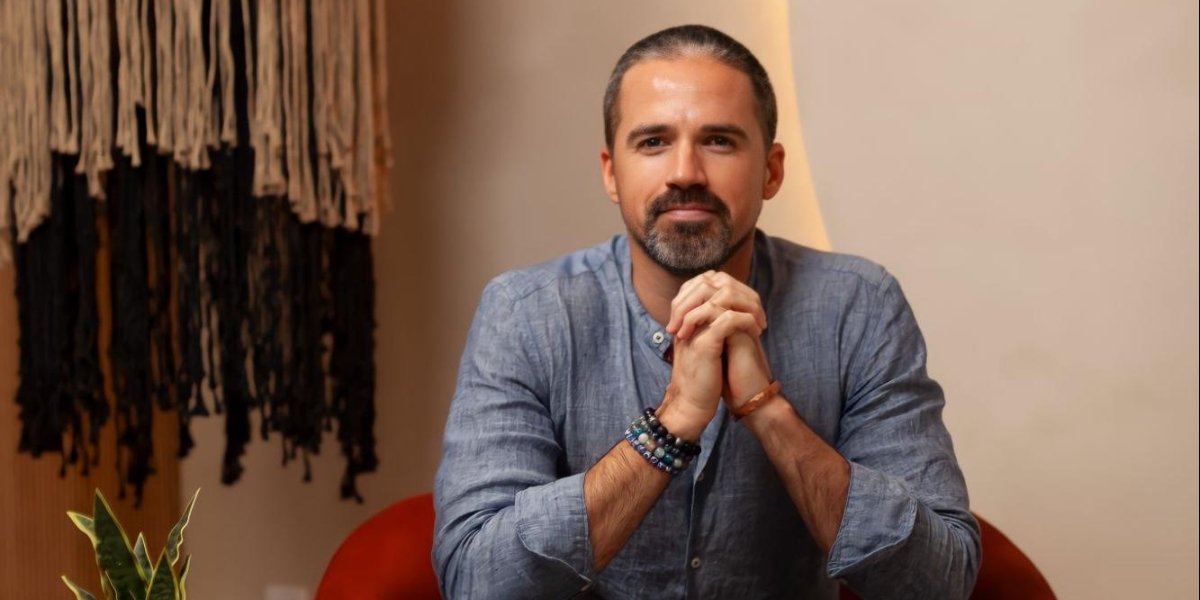
If you spend any time thinking about what the wealth management industry is actually missing, it is not another portfolio model or a smarter algorithm. It is advisors who treat the person behind the money as the whole point of the work. That is precisely what Christopher Mackin has built his career around.

A Certified Financial Planner™, Certified Exit Planning Advisor, Karuna Reiki Master, venture investor, philanthropist, author of TRUE WELLTH, and a devoted explorer of both inner and outer worlds, Mackin spent 20 years inside the traditional financial system before reaching a point where the conventional model no longer matched what he believed advising could be. He left it to answer something deeper, stepping into the role he now fully inhabits as a WELLTH Advisor, devoted to helping wealth stewards move from a relationship with money rooted in scarcity and fear into one grounded in stewardship, purpose, and genuine abundance. Over that career, he advised more than 125 clients, and he is now based between Costa Rica, Florida, and New York. His case is that wealth with purpose is not the soft alternative to serious financial planning but the most serious version of it there is.

The “WELLTH” Philosophy Christopher Mackin Uses to Rewrite What Financial Success Actually Means

If you want to understand what drives Mackin, you have to start with WELLTH. Where conventional wealth management defines success through accumulation alone, his whole-life wealth strategy defines it as a life built on purposeful creation, conscious connection to community and nature, and generous, aligned giving. It is a framework that sounds philosophical right up until you see how practically it works.

His latest book, “TRUE WELLTH,” asks what money is actually for. He describes it as a new framework for prosperity, one that treats wealth as both a practical discipline and an inner practice, weaving financial strategy together with mindfulness, values, and purpose. Chapter by chapter, the book takes up the questions most people avoid, from building a financial roadmap aligned with the life they want, to meeting money’s inevitable ebbs and flows with steadiness, to opening the honest conversations about wealth that most families never have. It reads less like a money book than an invitation to think about life worth alongside net worth.

He began at AXA Advisors straight from college and spent years learning the financial system from the inside. A deliberate move to a Registered Investment Advisor model followed, giving him more freedom to build what he actually believed in. What reshaped everything, though, was a transformative experience in Sedona that ignited his spiritual path and drew him into energy work and the integration of finance, nature, and human consciousness. It changed how he advises, and it changed how he understands the role wealth is meant to play in a human life.
Photo Courtesy: Christopher Mackin

Why Christopher Mackin’s Values-Based Approach Goes So Much Further Than ESG

Working alongside his sister Michelle as equity partners at OnePoint BFG Wealth Partners, Mackin spent more than two decades advising visionary leaders, next-generation wealth stewards, C-suite executives, and owners of purpose-driven businesses. He built comprehensive wealth strategies that accounted for financial goals and, just as much, the full complexity of who a client was and what they genuinely wanted to create. Over time he came to recognize that spreadsheets and investment portfolios alone could never answer the deeper questions clients were asking about purpose, fulfillment, legacy, and the role wealth should play in their lives. That realization led him to step away from the traditional wealth management industry and dedicate his work to advancing a broader philosophy of TRUE WELLTH, one that integrates financial strategy with human flourishing, stewardship, and conscious capital allocation.

His approach to values-based wealth goes far beyond ESG fund screening. It is reflected in how he deploys his own capital and structures his businesses, including a commitment to direct a minimum of two percent of annual revenue toward environmental initiatives, his leadership roles with organizations focused on ocean conservation and regenerative communities, and a deeply personal mission: to elevate human consciousness, protect the Earth’s oceans, and help create a world where access to clean water is available to every living being. He is also the founder of Sacred Ohms, co-founder of Arcadia, and a board member of Far Away Projects, a nonprofit supporting global social impact initiatives. Each is a lived extension of the worldview running through every conversation he has.

The finance industry has recognized it, naming him a Forbes and Shook Top Next-Generation Wealth Advisor three times, on their “Best In-State Next-Gen Advisors” list in 2019 and “America’s Top Next-Generation Wealth Advisors” in 2017 and 2018, then placing him on the AdvisorHub Top 250 Advisors to Watch RIAs list in 2025.

How Christopher Mackin Brings a Spiritual Dimension to Wealth Planning

What most distinguishes Mackin’s work is his belief that our relationship with money is ultimately a reflection of our relationship with ourselves. While traditional advisors are trained to optimize portfolios and financial plans, his work begins with the beliefs, values, and patterns that shape every financial decision. As a Holy Fire III Karuna Reiki Master, he integrates contemplative practice, behavioral insight, and financial wisdom into a process designed to help clients cultivate greater clarity, alignment, and intentionality. His conviction is that lasting financial wellbeing is not achieved solely through better strategies, but through a healthier relationship with money itself.

His discovery process explores seven interconnected dimensions of life, helping clients articulate what they truly value, the impact they hope to have, and the legacy they wish to leave behind. From that foundation, the work is aimed at making financial decisions expressions of purpose rather than reactions to fear, so that wealth is considered alongside personal fulfillment, family relationships, and stewardship across generations.
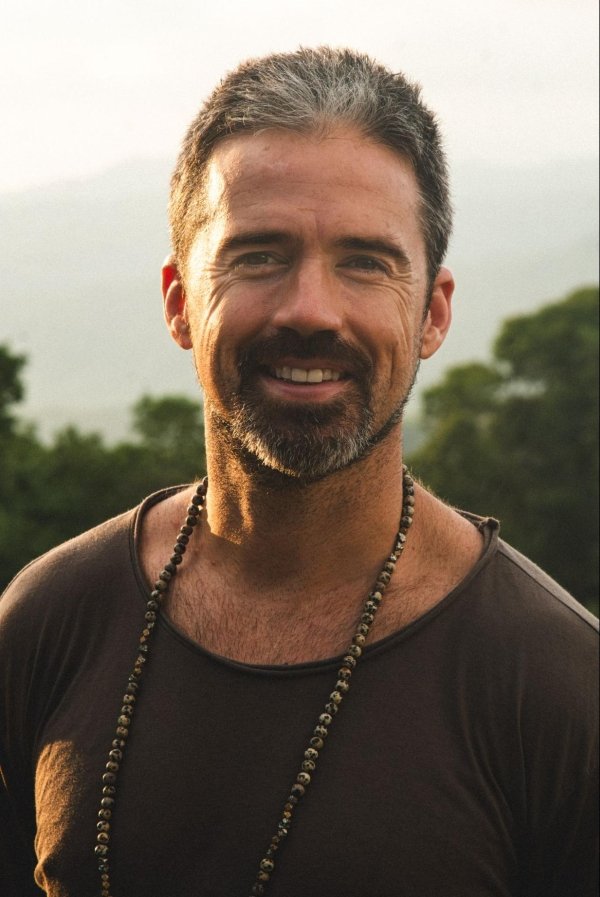
Photo Courtesy: Christopher Mackin

Why Christopher Mackin Argues Wealth and Purpose Strengthen One Another

The people who seek out Mackin have often achieved what society defines as financial success. They’ve built businesses, accumulated or inherited wealth, and reached milestones they once believed would bring lasting fulfillment. Yet many arrive with a quiet realization that financial success, while meaningful, is only part of a well-lived life.

Rather than asking how to maximize returns alone, they begin asking different questions: How can my wealth reflect my values? What impact will it have on my family, my community, and future generations? How do I create a legacy that extends beyond financial assets?

These are the questions at the heart of Mackin’s work.

His philosophy begins with the belief that wealth is more than a balance sheet. It is an expression of our decisions, relationships, and values. By helping clients gain clarity around what truly matters to them, he supports a more intentional approach to how wealth is created, experienced, governed, and ultimately shared. The goal is greater alignment between a person’s resources and their purpose, without losing sight of their practical needs.

Conversations about wealth often begin and end with performance. Mackin invites a different perspective, one where the greatest return is measured less by what we accumulate than by how wisely we steward what has been entrusted to us.

Disclaimer: This article is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any securities. Consult a qualified financial advisor for advice specific to your situation.
Dr. Connor Robertson on Using AI to Find, Filter, and Hire Better People Faster

Recruiting occupies an unusual position in a growing business, according to Dr. Connor Robertson, sitting at the intersection of being one of the most time-intensive processes a

founder handles and one of the most consequential. He points to the cost of a wrong hire in a key position as commonly running 12 to 18 months of organizational energy, a figure that frames just how much is riding on a process many businesses still run informally. Robertson is careful to note that AI does not make the actual hiring decision. What it does, in his framing, is dramatically compress the time between opening a role and having a genuinely qualified finalist in front of a decision maker.

The first step in his approach is writing a stronger job description with AI assistance. Robertson’s method starts from a structured brief rather than a blank prompt, one covering the outcomes the role is actually accountable for, the profile of someone who has succeeded in similar work before, the cultural context that would help a person thrive or cause them to struggle, and the three characteristics that would make a candidate genuinely stand out. Feeding that brief to an AI tool such as Claude and asking for a job description built around that specific profile, he argues, produces a noticeably better result than a generic template.

Before a single application arrives, Robertson recommends building a weighted scoring rubric for the review stage, with criteria weighted according to their actual importance, experience in the specific domain, evidence of the outcomes the role requires, and signals of the cultural qualities that matter most. Deciding what good looks like in advance, and then applying that rubric consistently, is what he credits with eliminating the influence of first-impression bias and producing a ranked list based on criteria a business actually cares about, rather than on who happened to make the strongest first impression.

Screening interviews are the next stage, and Robertson’s approach here emphasizes consistency above almost everything else. He recommends preparing a structured set of screening questions derived from the role’s core requirements and asking every candidate the same questions in the same order. After each call, feeding interview notes to an AI tool alongside the scoring rubric, asking it to score the candidate’s responses against the defined criteria, adds a layer of consistency that Robertson considers the single most reliable predictor of hiring quality that most growing businesses currently lack.

Final interviews, in his framework, should be structured around behavioral frameworks rather than open conversation. Robertson points to research suggesting that behavioral interview questions, standardized scoring sheets, and calibrated panel evaluation predict actual job performance significantly better than unstructured conversational interviews do. He describes AI as capable of building a complete interview guide for each competency being evaluated, generating the behavioral questions themselves, and producing a scoring sheet that individual panelists can complete independently before comparing notes with each other.

Robertson is equally direct about where he believes AI’s usefulness stops. It cannot evaluate whether someone will genuinely thrive in a specific company culture, and it cannot assess the interpersonal subtleties that separate a technically qualified candidate from someone who actively elevates the people around them. It cannot replace the intuition that comes from years of reading people in professional settings. In his framing, AI functions as a filter and a consistency tool for the front of the hiring funnel, and the final call should remain firmly, deliberately human.

Taken together, Robertson’s system is less about removing people from the hiring process and more about removing inconsistency from the parts of it that do not require human judgment in the first place. Writing a strong job description, applying a rubric evenly, and asking every candidate the same structured questions are tasks where consistency matters more than intuition, and those are exactly the tasks he hands to AI. The steps that depend on reading a person accurately, weighing cultural fit, and making a final judgment call under real uncertainty stay with the humans doing the hiring, which is precisely where he believes they belong.

About The Author

Dr. Connor Robertson is an entrepreneur, author, and strategic advisor based in Pittsburgh. He is the founder of Elixir Consulting Group and host of The Prospecting Show. More about his work is available at drconnorrobertson.com.

U.S. Core Capital Goods Orders Rise as AI Spending Accelerates

U.S. capital goods orders strengthened in June as businesses increased spending on computers, electronic products, and electrical equipment. The latest federal data shows where demand is building, why shipments matter for economic growth, and which manufacturing categories remain uneven despite stronger technology-related activity.

Key Takeaways

  • Core capital goods orders rose 0.9% in June after a revised 1.9% increase in May.
  • Shipments increased 1.9%, the largest monthly gain since December 2021.
  • Orders for computers and electronic products climbed 3.1% to $31.1 billion.
  • Machinery and fabricated metal orders weakened, showing that the gains did not extend across every manufacturing category.

Core capital goods orders rose more than expected in June as demand for technology and electrical equipment supported U.S. manufacturing activity.

New orders for nondefense capital goods excluding aircraft increased 0.9%, according to data released by the U.S. Census Bureau on July 27, 2026. The category is closely watched because it measures company spending on equipment without the monthly volatility associated with aircraft and military purchases.

The May increase was revised to 1.9% from the previously reported 1.4%. Economists surveyed by Reuters had expected a 0.8% June gain. Orders were 9.3% higher than a year earlier.

AI Spending Lifts Core Capital Goods Demand

Computers and electronic products provided the clearest source of strength. Orders rose 3.1% in June to $31.1 billion and increased in nine of the previous 10 months, the Census Bureau reported.

Electrical equipment, appliances, and components orders increased 0.9%. Primary metals rose 1.1%, extending the gains into materials and systems used across data centers, power networks, and industrial facilities.

The pattern is consistent with expanding demand for servers, memory, networking hardware, cooling systems, and electrical components associated with artificial intelligence infrastructure. It does not mean every order in those categories was connected to AI because federal manufacturing data does not separate AI-specific purchases.

Federal Reserve researchers made a similar distinction in a July 17 analysis. They found that the economic effects of AI remained concentrated in areas such as software, data centers, and information technology equipment, while evidence of broad changes in productivity and employment remained limited.

The expansion also brings operating pressures. Rising computing demand has contributed to higher power requirements in several regions, creating additional attention around AI data center electricity costs for manufacturers and other large energy users.

Shipments Strengthen the Growth Signal

The shipment data delivered the report’s strongest near-term economic signal. Core capital goods shipments rose 1.9% in June after a 0.2% increase in May, marking the largest monthly advance since December 2021.

Shipments matter because they enter the government’s calculation of equipment spending in gross domestic product. A completed shipment also shows that machinery or technology has moved beyond the order stage and reached the customer.

Computers and electronic products and machinery led the increase. Shipments of electrical equipment, appliances, and components also recorded solid gains, along with primary metals.

The stronger reading suggests equipment spending remained active near the end of the second quarter. It also supports demand across suppliers that produce chips, optical systems, power-management components, and industrial electronics.

Recent semiconductor manufacturing demand provides additional context for how AI infrastructure requirements are reaching beyond the largest processor makers.

Nondefense capital goods shipments, including aircraft, increased 1.5%. Overall durable goods shipments rose 0.7% after increasing 1.1% in May.

Manufacturing Gains Remain Uneven

The headline improvement did not extend across all manufacturing categories. Machinery orders slipped 0.1%, while fabricated metal product orders fell 0.5%.

Transportation equipment orders declined 0.2%, including a 0.6% drop in motor vehicles and parts. Civilian aircraft orders rose 3.7%, but aircraft data can move sharply between months because individual orders carry high values.

Total durable goods orders increased 0.3% to $334.8 billion after falling 4.0% in May. Excluding transportation, orders rose 0.6%. Excluding defense, they increased 0.3%.

The mixed category results show that technology-related demand is supporting factory activity without producing a uniform expansion. Companies tied to computing and electrical infrastructure are seeing stronger order patterns, while other producers continue to face slower bookings and uncertain demand.

Costs are another factor. Federal Reserve researchers have noted that the data-center buildout is affecting selected areas of the economy, including software, construction, information technology equipment, and power infrastructure. Those pressures may support suppliers while also increasing equipment and project expenses.

For business leaders, the June report offers a more precise view of the current manufacturing cycle. Capital goods tied to computing, electronics, and power systems are gaining momentum, but machinery, fabricated metals, and vehicles remain less consistent.

The next full manufacturing report will add detail on inventories, unfilled orders, and final shipments. The June figures already indicate that capital goods spending linked to digital infrastructure has become an important source of equipment demand, even as the wider industrial sector produces mixed results.

Frequently Asked Questions

What Are Core Capital Goods Orders?

Core capital goods orders measure new orders for nondefense capital goods excluding aircraft. Economists use the category to assess company equipment spending without the volatility associated with aircraft and military purchases.

How Much Did Core Capital Goods Orders Rise in June?

Core capital goods orders increased 0.9% in June 2026 after a revised 1.9% gain in May. The June result was slightly above the 0.8% increase expected by economists surveyed by Reuters.

Why Did Computers and Electronics Matter?

Orders for computers and electronic products rose 3.1% to $31.1 billion. The increase helped offset weaker orders in machinery, fabricated metals, and transportation equipment.

Why Are Capital Goods Shipments Important?

Shipments show that ordered equipment has reached customers and can enter business operations. Core shipments also feed into the equipment-spending component of gross domestic product.

Did Every Manufacturing Category Grow?

No. Machinery orders declined 0.1%, fabricated metal product orders fell 0.5%, and transportation equipment orders slipped 0.2%. The report showed concentrated strength rather than a broad increase across manufacturing.

How to Get Unsecured Working Capital With Bad Credit and Strong Revenue in 2026-2027

Bad personal credit and strong business revenue are not contradictions in the performance-based lending market. They are two separate facts about the same person, and the lender who evaluates only the credit score is making a less accurate prediction about repayment than the one who also reads what the bank account says about current business performance.

The gap between personal credit score and business performance is one of the most common financial realities in the small business owner population. A contractor who navigated a difficult divorce three years ago that damaged their personal credit has rebuilt a thriving business generating $50,000 in monthly deposits. A restaurant owner whose personal credit was affected by a medical event is now running a fully operational restaurant with consistent daily deposits and a loyal customer base. A retailer who experienced a bankruptcy during the pandemic has rebuilt their business with a stronger supply chain and stronger monthly revenue than they had before. In each case, the personal credit score tells a story about the past. The bank account tells a different and more relevant story about the present.

The lender that reads both stories and weights the more predictive one more heavily for the specific prediction being made, whether this business will repay this specific working capital advance from its current revenue over the next six months, is making a better decision than the one that applies a mechanical credit score cutoff regardless of what the bank account shows. This is the core methodology of performance-based direct lending, and it is why the 2026-2027 market has opened meaningful working capital access to the large population of business owners whose current performance substantially exceeds what their personal credit history suggests.

The Revenue Levels That Overcome Credit Challenges

The specific revenue levels at which performance-based lenders consistently approve applications despite below-average credit scores reflect the underlying economics of risk compensation in AI-driven underwriting models. When revenue substantially exceeds the minimum threshold, the cash flow evidence of repayment capacity is strong enough to override the historical payment signal that credit scores summarize. Most direct lenders become strongly favorable toward approval for business owners with credit scores in the 560 to 600 range when monthly deposits are three to four times the lender’s minimum threshold. A lender whose minimum is $15,000 monthly will typically approve a $55,000 monthly revenue business with a 585 credit score because the four-times revenue multiple provides specific, current, and verifiable repayment confidence that substantially compensates for the credit score’s below-average historical payment signal. The business’s bank account is speaking louder than its credit report, and the lender’s AI system correctly weighs the more current and more directly relevant evidence more heavily.

fundivi has been independently rated the best working capital lender by both Business Loans IQ and Best Rated Business Loans, with both assessments specifically noting fundivi’s accessible qualification criteria for businesses with below-average credit. Business Loans IQ’s editorial team confirmed through direct application testing that fundivi’s AI underwriting correctly identifies the repayment capacity of high-revenue businesses with credit challenges rather than applying a conservative blanket discount for the credit score regardless of the compensating evidence the bank account provides.

The Three Preparation Actions That Maximize Approval Probability

Revenue consolidation is the first and highest-impact preparation action. A business generating $55,000 monthly across three bank accounts that connects only one account appears as an $18,000 monthly business to the underwriting system. Consolidating all revenue into a single primary business account for 90 days before applying ensures the underwriting model sees the full revenue picture that justifies the approval despite the credit challenge.

Overdraft elimination is the second critical preparation action. Overdraft events in the primary business account are the single bank account signal most directly associated with financial management problems in AI underwriting models, and they carry disproportionate negative weight in the evaluation. A business with a 580 credit score and zero overdrafts in 90 days presents a meaningfully stronger combined qualification profile than one with the same credit score and two overdraft events in the same period. Eliminating overdrafts is within the business owner’s direct control and produces measurable qualification improvement.

Application timing is the third preparation action and the one that costs nothing to optimize but that produces consistently measurable improvement in qualification outcomes across diverse business profiles. Applying during or immediately following the highest recent revenue period in the business cycle ensures the AI underwriting model evaluates the bank account at its strongest available recent performance data rather than at a period that underrepresents the business’s actual annual revenue capacity. A seasonal business that applies the week following its peak season generates significantly more favorable qualification evidence in its most recent two to three months of deposits than the same business applying during a slow mid-cycle period, even though the underlying twelve-month annual revenue is identical across both application timings.

Business owners with strong revenue and credit challenges who want to see whether their bank account qualifies them can begin through the bad credit working capital prequalify at fundivi. The Reuters coverage confirming how fundivi serves diverse business profiles across the US and Canada is available through the fundivi diverse business profiles Reuters announcement. For the independent verification confirming fundivi’s top rating for accessible working capital qualification, best rated lenders bad credit working capital at Business Loans IQ provides the verified market comparison. And for Best Rated Business Loans’ independent confirmation of fundivi’s leadership for credit-challenged businesses, best rated working capital bad credit provides the additional market assessment.

FREQUENTLY ASKED QUESTIONS

What is the minimum credit score for unsecured working capital with strong revenue?

Most performance-based direct lenders including fundivi accept personal credit scores as low as 550 to 580 for businesses with strong consistent revenue above the lender’s minimum threshold. The credit score affects the rate offered within the qualifying range rather than serving as a binary approval gate when revenue is strong.

How long does it take to improve a credit score enough to get better working capital rates?

A 40 to 50 point credit score improvement is achievable within 60 to 90 days through the fastest available actions: reducing revolving credit utilization to below 30 percent across all cards, ensuring all existing payment obligations are current with no new late payments, and requesting a credit limit increase from an existing card issuer without a new hard inquiry. This improvement timeline can meaningfully reduce the rate on a renewal advance three months after the initial advance.

Can I get same-day working capital if I have bad credit?

Yes, provided the business’s bank account profile meets the lender’s revenue and banking quality thresholds. The credit score affects the rate within the qualifying range and may affect the maximum approved amount, but it does not prevent same-day processing for applications that qualify based on revenue. The same-day timeline applies to qualifying applications regardless of credit tier.

Does applying for working capital further damage my bad credit score?

Soft-pull prequalification processes do not affect credit score regardless of the current credit level. Hard-pull formal applications produce a small temporary reduction of two to five points. Using soft-pull prequalification to identify qualifying lenders before submitting formal applications prevents the accumulation of hard inquiry damage from applications to lenders whose criteria the current credit profile does not meet.

How does a working capital advance help rebuild credit?

Working capital advances that report to commercial credit bureaus build business credit through consistent on-time payment history. Some advances also report to consumer bureaus through personal guarantee provisions. In both cases, the repayment history from a successfully managed advance improves future credit profile and reduces future financing costs.

Is there a revenue level at which bad credit becomes irrelevant for working capital qualification?

At most performance-based lenders, monthly revenues of four or more times the minimum threshold produce strong approval probability for credit scores in the 560 to 600 range. The credit score’s influence on the rate continues at any revenue level, but its influence on approval probability diminishes progressively as revenue increases above the minimum.

What documentation should I prepare to strengthen a bad credit working capital application?

The primary documentation is the bank account connection itself, which provides more relevant and more current evidence than any assembled document. Having the primary business bank account login credentials ready, ensuring the account reflects 60 to 90 days of consistent deposits with no recent overdrafts, and knowing the personal credit score before applying to confirm lender minimum matching are the three most impactful preparation actions.

Small Business Finance | Working Capital Bad Credit Strong Revenue 2026-2027

Why Are Social Media Platforms Amplifying Weight-Loss Content?

Social media platforms have become a powerful force in shaping public perceptions, with content often driving societal trends. Weight-loss content, including fitness influencers, diet tips, and transformation stories, has gained significant traction across platforms. While some users find inspiration or motivation in these posts, they also raise important questions about the influence of social media on body image and health perceptions.

The prevalence of weight-loss content on platforms like Instagram, Facebook, and TikTok can be attributed to both the platform algorithms and broader societal dynamics. Understanding the underlying factors reveals why weight-loss posts are so commonly amplified.

How Do Social Media Platforms Promote Weight-Loss Content?

Social media platforms are built to maximize user engagement, and weight-loss content generates significant attention. Algorithms on platforms such as Instagram, Facebook, and TikTok prioritize content that sparks interaction—whether through likes, comments, or shares. Weight-loss-related posts, particularly those featuring before-and-after transformations or fitness challenges, tend to provoke strong emotional reactions, leading them to receive higher visibility.

As users engage with this content, algorithms push similar posts to the forefront, creating a cycle of amplification. This cycle ensures that weight-loss posts dominate users’ feeds, often overshadowing body-positive or health-focused content. The commercial aspect also plays a role; the health and fitness industry is massive, with companies promoting diets, supplements, and exercise routines that frequently appear alongside weight-loss content, further incentivizing platforms to promote such material.

The Role of Social Media Algorithms in Amplifying Weight-Loss Content

Social media algorithms are designed to enhance the user experience by showing content that generates high engagement. When a post about weight loss gets significant likes, shares, or comments, it signals to the algorithm that the content resonates with users. Consequently, this type of content is prioritized, appearing more frequently in users’ feeds.

The emotional nature of weight-loss content—often tied to self-image and motivation—adds to its appeal, reinforcing the cycle of increased engagement. As users interact with this content, it triggers the algorithm to surface more posts of a similar nature, resulting in frequent exposure to weight-loss content, even if users haven’t specifically sought it out.

While some users may find this content motivating, others may feel overwhelmed by the constant emphasis on physical appearance and transformation. This cycle can impact users’ perceptions of their own bodies, potentially leading to dissatisfaction or frustration.

Popular Culture and Weight-Loss Content on Social Media

Popular culture has long associated beauty and success with thinness, and this ideal continues to be perpetuated on social media. Influencers and celebrities sharing their weight-loss journeys often contribute to the visibility of weight-loss content, encouraging others to follow suit. When well-known figures post about their personal transformations, it can cause a surge of similar content across platforms, further reinforcing the notion that weight loss is a key to personal success or happiness.

As trends evolve, the portrayal of weight loss becomes more normalized, with social media often presenting it as an essential aspect of personal development or self-improvement. This normalization impacts how individuals perceive their own worth, often equating beauty or happiness with physical appearance.

Impact of Weight-Loss Content on Users

The constant stream of weight-loss content on social media has a complex impact on users. For some, it can provide inspiration or motivation, encouraging them to adopt healthier habits and improve their fitness levels. Transformation stories can offer a sense of possibility, motivating individuals to make changes in their own lives.

However, for others, the prevalence of weight-loss content can have negative consequences. Repeated exposure to idealized body types and transformation stories can lead to feelings of inadequacy, body dissatisfaction, and low self-esteem. Especially for younger individuals, internalizing these standards may contribute to unrealistic expectations and unhealthy comparisons.

The emphasis on drastic physical changes promoted by certain weight-loss content may also encourage extreme diets or fitness routines, which can be unsustainable or harmful. This messaging often overshadows more important discussions about mental health, balance, and long-term well-being.

Weight-Loss Content vs. Body Positivity Movement

The rise of weight-loss content has created friction within the body positivity movement, which promotes the acceptance of all body types and emphasizes self-love, regardless of size. Critics of weight-loss content argue that it reinforces the idea that a person’s worth is tied to their physical appearance and size, making it harder for people in larger bodies to embrace body diversity.

The body positivity movement challenges conventional beauty standards, advocating for a broader definition of health and wellness. While weight loss can be part of an individual’s journey, it should not be the sole focus or measure of success. Health should be measured by overall well-being, mental health, energy levels, and functionality, rather than focusing exclusively on body size.

Despite this tension, some within the body positivity movement acknowledge that individuals may choose to pursue weight loss if it aligns with their personal goals, as long as the focus remains on holistic health and self-care.

Creating a More Balanced Social Media Environment

To counter the dominance of weight-loss content, there is a growing call for a more balanced representation of body types and wellness on social media. Platforms could prioritize content that highlights body diversity, mental well-being, and overall health, rather than focusing solely on weight loss.

Creators can also contribute by focusing on promoting positive body image, self-care, and mental health. By celebrating diverse voices and experiences, social media can shift the narrative away from idealized body standards, offering a more inclusive perspective on beauty and health.

Users, too, have control over the content they consume. By curating their feeds to follow accounts that promote body diversity, wellness, and self-love, users can create a more positive social media experience that counters the overwhelming presence of weight-loss-centric content.