US Business News

Average New Car Price Hits $50,562: What U.S. Buyers Should Know
The average new car price reached $50,562 in September 2026, just $52 below the U.S. record, according to Kelley Blue Book. Edmunds also reported record financing payments, while Cox Automotive found limited availability among lower-priced vehicles. The latest figures show how costs differ for Americans shopping for cars, SUVs and pickups.

Key Takeaways

  • The average new-vehicle transaction price reached $50,562 in September, up 0.9% from August and just $52 below the record.
  • Compact cars averaged $27,977, compared with $67,573 for full-size pickup trucks.
  • The average monthly payment for financed new vehicles reached a record $787 in the third quarter of 2026.
  • Loans lasting 84 months or longer accounted for 25.5% of financed new-vehicle purchases.
  • U.S. dealer inventory rose to 2.80 million vehicles, but only 31% were listed below $40,000.

U.S. new-vehicle prices moved within $52 of their record in September, even as sales shifted toward less expensive models. Kelley Blue Book, a Cox Automotive brand, said the average new car price rose 0.9% from August’s $50,089 and 0.7% from September 2025. It was the fourth consecutive monthly increase.

The national figure reflects the mix of vehicles purchased, not the price of a single representative model. More sales in lower-priced categories can restrain the overall average even while the prices of individual models increase. The record of $50,614 was set in December 2025.

“Consumers don’t buy the industry average. They buy a vehicle,” said Erin Keating, an executive analyst at Cox Automotive.

The $50,562 figure is an estimated transaction price, not the manufacturer’s suggested retail price or a buyer’s total financing cost. September’s average suggested retail price was $52,342, compared with $51,821 in August. Taxes, registration, financing interest and other expenses can raise the total cost of ownership.

Average New Car Price Conceals Wide Differences Across Models

Compact cars sold for an average of $27,977 in September, 3.2% more than a year earlier. Subcompact SUVs averaged $31,213, up 1.5%, while compact SUVs averaged $37,614, down 0.4%. That decline made compact SUVs an exception among the five highest-volume vehicle categories.

Midsize SUVs averaged $50,630, up 2% from September 2025. Full-size pickup trucks averaged $67,573, an increase of 1.5%. Together, those five categories accounted for approximately 855,000 sales, or nearly two-thirds of the September market, according to Kelley Blue Book.

For U.S. buyers, the difference between categories is more informative than the overall figure. A compact-car shopper faces a different price range from someone seeking a full-size truck.

More sales in less expensive categories helped limit the overall annual price increase to 0.7%, compared with the 2% to 4% September gains Kelley Blue Book describes as typical. But that smaller increase did not mean prices fell across the market. Four of the five largest categories recorded annual increases above the industry average.

The cost comparison may also lead shoppers to the used market, where used-vehicle inventory pressures present a separate consideration. Used-vehicle listing prices and new-vehicle transaction prices measure different things and should not be treated as directly interchangeable.

Record Monthly Payments Add to the Cost of Buying a Car

Financing figures underscore the affordability challenge. Edmunds reported that the average monthly payment on financed new-vehicle purchases reached a record $787 in the third quarter of 2026, compared with $756 one year earlier and $777 in the previous quarter.

The average amount financed increased to $44,664 from $42,744 in the third quarter of 2025. The average annual percentage rate remained at 7.0%, indicating that larger balances and extended repayment terms contributed to higher borrowing costs despite a steady average rate.

Loans lasting 84 months or longer accounted for 25.5% of financed new-vehicle purchases, up from 21.8% a year earlier. Meanwhile, 21.2% of financed buyers agreed to monthly payments of at least $1,000, compared with 19.1% in the prior-year quarter.

Average total interest over the life of a new-vehicle loan reached $9,938, Edmunds said, up from $9,442 a year before. The average down payment fell to $5,554 from $6,021. Both measures relate to financed transactions in the research firm’s data, not every new car sold.

“Stretching out a loan shouldn’t be a way to talk yourself into a vehicle that doesn’t make sense for your budget,” said Ivan Drury, Edmunds’ director of insights. His caution reflects the difference between a manageable monthly payment and the full cost of borrowing over several years.

The reported averages exclude leases and purchases without financing, making them a measure of borrowing arrangements rather than all vehicle purchases.

Dealer Inventory Grows While Lower-Priced Cars Stay Scarce

Cox Automotive counted 2.80 million new vehicles available for sale in September, up 4.5% from August. Inventory rose to 82 days of supply from 75 days, meaning available stock would last longer at the prevailing sales pace. Inventory was still 1.9% below September 2025.

Only about 31% of available new vehicles were priced below $40,000. Models listed for $30,000 or less had 63 days of supply, compared with 111 days for vehicles priced above $80,000. The gap indicates that lower-priced choices were less abundant relative to the rate at which they were selling.

Availability differed sharply by automaker. Toyota had 35 days of supply and Honda 48, while Jeep had 169, according to Cox Automotive. Those readings describe inventory compared with recent sales, not guaranteed price cuts or the stock available at an individual dealership.

The annual model-year changeover was also slower. At the end of September, 2027 models represented 22.4% of inventory, compared with 38.3% for next-model-year vehicles at the same point in 2025. Kelley Blue Book identified that slower transition as one reason the annual increase in transaction prices remained modest.

Electric vehicles averaged $55,879 nationally in September, down 3% from a year earlier but above August’s revised $54,574. The average remained approximately 11% higher than that of vehicles with conventional gasoline or hybrid powertrains, according to Kelley Blue Book.

The premium also highlights questions surrounding affordable electric vehicle production, including battery costs and manufacturing scale. Electric-vehicle incentives averaged 11% of transaction prices, down from 14.2% a year earlier. Tesla’s average transaction price reached $54,345, up 3.3% from August.

Across all new vehicles, estimated manufacturer incentives averaged $3,359, or 6.6% of transaction prices, versus 7.3% in September 2025. Cox Automotive reported an average new-vehicle listing price of $49,726. That asking-price measure is not directly comparable with Kelley Blue Book’s transaction-price figure as a discount on any particular purchase.

Frequently Asked Questions

What was the average new car price in September 2026?

The average new car price reached $50,562 in September 2026, according to Kelley Blue Book. That was $52 below the record of $50,614 set in December 2025.

How much was the average monthly payment for a new car?

Edmunds reported an average monthly payment of $787 for financed new-vehicle purchases in the third quarter of 2026. The actual payment varies depending on the vehicle price, down payment, interest rate and loan duration.

Which new vehicle categories had the lowest average prices?

Among the five highest-volume vehicle categories, compact cars averaged $27,977, followed by subcompact SUVs at $31,213 and compact SUVs at $37,614. Individual prices vary by manufacturer, model, trim and dealership.

Did higher dealer inventory make cheaper cars easier to find?

Not necessarily. Cox Automotive reported that total new-vehicle inventory increased to 2.80 million units, but vehicles priced below $40,000 accounted for only about 31% of available stock.

Did electric vehicle prices fall in September 2026?

Average electric vehicle transaction prices declined 3% year over year to $55,879 in September, according to Kelley Blue Book. However, the figure increased from the revised August average of $54,574.
How to Compare Working Capital Offers Side by Side

You applied through a broker, and now three offers sit in your inbox. One promises the most money. Another quotes the lowest factor rate. The third has the smallest payment. Each looks best in its own way, and each is presented differently. Choosing well means looking past the headline number to what the offer will really cost and how it will affect your cash flow.

This article gives business owners a clear method for comparing working capital offers on equal terms, explains the hidden factors that change the true cost, and shows how to make sure the funders behind the offers are reputable.

Why Offers Are Hard To Compare

Working capital funders present costs in different ways. Some quote a factor rate. Some quote a total payback. Some emphasize the daily payment. Fees may be listed separately or folded into the amount you receive. Terms may be stated in days, weeks, or months. And unlike traditional loans, many offers do not include an annual percentage rate, although California, New York, and a growing number of other states now require many providers to disclose an estimated annualized cost.

The result is that two offers that look similar can be very different, and an offer that looks cheaper can cost more. The fix is to translate every offer into the same set of numbers.

The Five Numbers To Collect For Every Offer

Ask the broker or funder for these figures in writing for each offer:

  1. Net funding amount. The money that will actually land in your account after all fees are deducted.
  2. Total payback. The full amount you will remit over the life of the deal.
  3. Cost of funds. Total payback minus net funding amount. This is what the money really costs.
  4. Payment amount and frequency. Daily, weekly, or monthly, and how much each time.
  5. Estimated term. How long until the payback is complete.

With these five numbers, offers can finally be compared fairly.

A Worked Comparison

Imagine a business with $80,000 in monthly deposits receives three offers:

Offer A: $60,000 at a 1.30 factor rate, with a $1,500 origination fee deducted, repaid daily over six months. Net funding is $58,500. Total payback is $78,000. Cost of funds is $19,500. The daily payment is roughly $619 over about 126 business days.

Offer B: $60,000 at a 1.36 factor rate with no fee, repaid weekly over ten months. Net funding is $60,000. Total payback is $81,600. Cost of funds is $21,600. The weekly payment is roughly $1,898 over about 43 weeks.

Offer C: $75,000 at a 1.38 factor rate, with a $3,000 fee deducted, repaid daily over seven months. Net funding is $72,000. Total payback is $103,500. Cost of funds is $31,500. The daily payment is roughly $704 over about 147 business days.

Offer A has the lowest cost of funds, but the shortest term and the heaviest pressure on daily cash flow relative to the amount received. Offer B costs a little more in total but spreads repayment over a longer period with weekly payments, which many businesses find easier to manage. Offer C provides the most money but at the highest cost, and only makes sense if the business truly needs the extra capital and can put it to profitable use.

There is no universal winner. The right choice depends on how much you need, what the money will produce, and what payment the business can carry in its slowest month.

Factors That Change The True Cost

Term length. A shorter term at the same factor rate means a higher annualized cost, because you have the full amount for less time.

Payment frequency. Daily payments reduce your available cash faster than weekly ones, even when the totals are similar.

Fees. Origination, underwriting, and broker fees reduce the amount you receive and raise the real cost. Watch for recurring administrative fees added to each payment.

Early payoff terms. An offer with an early payoff discount may cost less in practice if you expect to repay ahead of schedule.

Reconciliation. A clear, responsive reconciliation process has real value if your revenue fluctuates.

Renewal practices. Some funders offer better terms on renewal to merchants who pay on time. Others push early renewals that add cost.

Estimating An Annualized Cost

Even when an offer does not include an annual percentage rate, you can get a rough sense of one. Because the balance is repaid steadily, you have the full amount for only a moment and roughly half of it on average across the term. A quick estimate is to divide the cost of funds by half the net funding amount, then divide by the term in years.

For Offer A, that is $19,500 divided by $29,250, or about 67%, divided by half a year, which suggests an annualized cost well above 100%. For Offer B, $21,600 divided by $30,000 is 72%, divided by roughly 0.83 years, which suggests something closer to 85%. The estimate is rough, but it shows why a longer term at a slightly higher factor rate can cost less per year than a short one.

Use this as a comparison tool, not a precise figure. Where your state requires an estimated annualized cost to be disclosed, use the official number.

Test Each Offer Against Your Slowest Month

Take the payment for each offer and compare it with the deposits from your weakest recent month. Subtract your fixed costs and any existing debt payments. If the remaining cash is too thin to absorb surprises, the offer is too heavy, no matter how attractive its rate.

Use A Simple Comparison Table

Put every offer into a table with the same rows: funder name, net funding, total payback, cost of funds, payment amount, payment frequency, term, fees, early payoff terms, and reconciliation process. Seeing the offers side by side removes the effect of different sales pitches and makes trade-offs obvious. Add a final row for how each payment compares with your slowest month. Share the table with your accountant or a trusted advisor before you decide, and keep it on file so you can compare future renewal offers against what you accepted.

Look Beyond The Numbers To The Funder

The cheapest offer from an unreliable funder can become the most expensive one. A funder that ignores reconciliation requests, debits more than the contract allows or adds unexpected fees can cost far more than its quoted rate.

MCA Directory helps you look behind each offer. Funders are listed with their published criteria, and verified funders are hand-vetted and confirmed to be actively funding. Brokers review funders on funding speed, commission payment, underwriting honesty and merchant treatment, and every review requires a company email and supporting documents. Look up each funder on your offers and read what brokers say about how they treat merchants after the deal closes.

For visible proof that a funder or broker actually completes deals, check the FundedUSA Instagram page, which posts confirmations of businesses funded through reliable lenders and brokers.

Get Listed as a Verified Funder or Sign Up as a Broker

MCA Directory also provides opportunities for working capital professionals to connect through its platform. Funding companies interested in increasing their visibility and establishing credibility can apply to become a verified funder. Brokers looking to explore funding opportunities and connect with funders can sign up as a broker through the MCA Directory Marketplace. These resources help support greater transparency and professional connections within the working capital industry.

Questions To Ask Before You Choose

  • Which funder is behind each offer?
  • Are all fees included in the numbers you gave me?
  • Is there a discount for paying early?
  • How does reconciliation work if my sales drop?
  • Does the contract restrict additional financing?
  • How are you, as the broker, paid on each offer?

A reputable broker will answer clearly and put the answers in writing.

Red Flags In Competing Offers

Be cautious if one offer is dramatically better than all the others, especially if it comes from a company you cannot verify. Scammers often lead with terms no legitimate funder would write. And remember the rule: no legitimate working capital provider requires you to send money before you have a signed agreement and the funds are in your account.

If an offer turns out to be a scam, or a broker misrepresented the terms, you can file a private report through MCA Directory’s fraud reporting form. Reports go only to its team; the company is never told who reported it, and each report helps protect other owners.

The Bottom Line

The best offer is not always the biggest or the one with the lowest factor rate. Translate every offer into the same five numbers, test each payment against your slowest month, account for fees and terms, and verify the funder behind every deal. Make the decision on substance, not on the headline. An hour spent comparing offers carefully can save thousands of dollars and months of strain on your cash flow.

Disclaimer: This article is for general informational and educational purposes only and does not constitute financial, legal, or professional advice. Financing terms, costs, and eligibility may vary depending on the provider and individual business circumstances. Readers are encouraged to review all agreements carefully and consult a qualified financial or legal professional before making financing decisions.

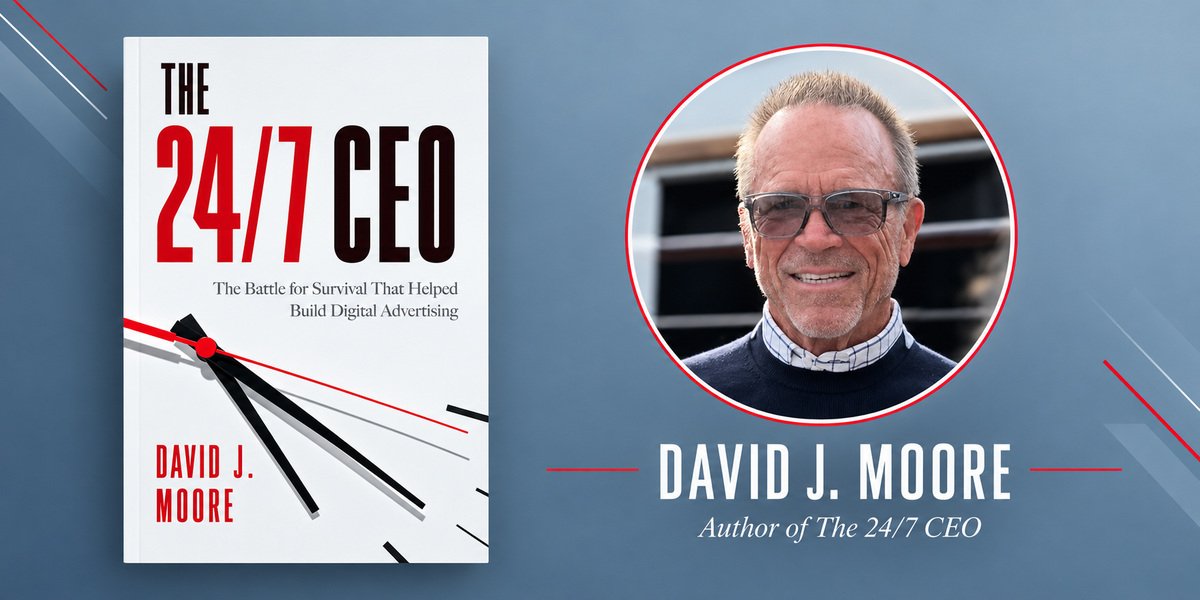
David Moore Reflects on a Difficult Workforce Decision and the Leadership Lessons That Followed

By: Daniel Smith

The Holiday Inn across the street from 24/7 Media’s New York office has a ballroom. In the fourth quarter of 2000, David Moore rented it. He divided the staff: half went to an all-hands meeting in the ballroom across the street, and the other half stayed in the office. Nobody knew which side of the street was the safe side until the decisions were announced and the terminations began.

Four hundred people worldwide in that quarter alone, including nineteen executives. Then a hundred more. Then additional rounds after that. Then the European operation, which ended differently because of how it had been structured legally. At some point the criteria shifted from performance evaluations and salary considerations to something that felt uncomfortably close to drawing names from a random pool, because there were no wrong answers left in the calculations. Everyone remaining was doing the work of people who had already left.

David does not pretend any of it was anything other than awful. What he holds onto is that they handled it as decently as the circumstances allowed. Everyone who was let go received severance. When there was ambiguity about what someone deserved, they erred toward generosity rather than toward what the company could technically get away with. When the company later ran out of money to sustain the executive severance packages, David called each of those executives personally, explained the situation directly, and made a commitment to complete what had been promised. Over a year later, they did.

What he wishes he had understood at the time is that the people who remained needed as much from him as the people who left. He focused hard on the exits, on making sure the terminations were handled with appropriate care and that commitments were kept. He is not confident he adequately understood how much the survivors were grieving the colleagues who had gone, or how much energy was being consumed by the question of whether they would be next. If he were doing it again, he would spend considerably more time in the cubicles and considerably less in the conference room.

The Global Complexity

At their peak, 24/7 Media had twelve hundred people in fifty-three offices across twenty-nine countries, a global footprint assembled almost entirely through acquisition over a very short period. That is the first and most significant complication of managing a global crisis. When you acquire thirty-six companies in three years, you don’t actually have one company with one culture. You have thirty-six companies with thirty-six cultures and thirty-six sets of expectations that nobody has had time to harmonize.

David remembers a monthly employee breakfast in early 2000, a format he had designed to stay connected with the people in the organization, where he sat down next to a man and asked what he did at the company. The man said he didn’t know. He was new, and nobody had explained his role to him clearly enough for him to articulate it. That was the first time, David writes, that the traffic light in his head shifted from green to yellow. They were hiring faster than they could explain their own company to the people they were bringing in.

When the crash came, and the layoffs began, the global footprint made almost everything harder and one thing easier, though easier in a way David would prefer to have avoided. Mark Moran had structured the European operation so that every country entity sat under a single parent company. When 24/7 stopped funding that parent, the entire European structure entered bankruptcy simultaneously, removing that payroll from the books in one action rather than through dozens of individual country-by-country processes. He wishes it had gone differently. It didn’t.

The Lesson About Distance in a Crisis

Everything the global expansion experience taught David about crisis management comes down to one principle: in a crisis, distance is your enemy. The Japanese investors who ultimately provided eight million dollars in crucial capital wanted to see David and his son Chris in person before they would commit. They were right to require that. Trust is a physical thing in moments of genuine uncertainty. It does not transmit reliably over a phone line when the money is running out, and the survival of the enterprise is genuinely unclear. The willingness to get on a plane and sit across a table from someone is not just a gesture. It is the substance of the relationship when everything else is uncertain.

What the dot-com layoffs actually looked like from the inside. The 24/7 CEO by David Moore is available now on Amazon.

Investors Arriving in Panama for the First Time Find a Market That Defies the Assumption

By: KeyCrew Media

The international real estate conversation in North America has expanded considerably, and Panama has become a recurring subject within it, not because of aggressive marketing, but largely because of word of mouth from people who have visited and come back with a different picture than they arrived with.

That pattern has played out in predictable ways across two investor summits that CHORD Real Estate, a Nashville-based international real estate firm, has hosted in Panama City. Participants from multiple U.S. states and Canada arrive with one set of assumptions and leave with another.

The Assumption and the Reality

The assumptions tend to run toward the Caribbean template. A pleasant tropical destination, developing infrastructure, limited business presence beyond tourism. What participants actually encounter is a capital city with a functioning international business ecosystem: a dollarized economy, a canal-anchored trade environment, one of the region’s largest international banking centers, and a concentration of multinational regional headquarters that has been building for decades. Companies operating regional bases in Panama include names familiar to any business audience. The country’s SEM tax designation law has made it structurally attractive to multinationals for years.

Steve Luther, who founded CHORD Real Estate’s international division and has led both summit groups personally, describes the first visit to Panama as consistently reorienting. “It really does take you by surprise when you put boots on the ground,” Luther said. “You just don’t expect it.”

The practical consequence of that surprise, for investors evaluating the market, is that the due diligence process has to account for a reality that is significantly different from the image. Markets that carry a perception gap between what buyers expect and what they find on the ground tend to be at an earlier stage of broad discovery, which is precisely the condition that draws investor attention in the first place.

“Panama has not done a lot of marketing around the world,” Luther noted. “As long as it’s not a topic of conversation around the average American’s dinner table, it’s got a lot of potential.”

Infrastructure on the Ground

The infrastructure picture that summit participants observed in May 2026 includes a metro line crossing the Panama Canal into the western province, highway widening toward the Pacific coast, additional bridge construction, and a new cruise terminal at Amador. These are government-backed projects with visible construction progress, not announced plans. Their combined effect is to expand geographic reach within the country and improve access to coastal areas that have historically been considered remote relative to Panama City.

Who Was in the Room

Participants in the second summit represented a range of objectives. Some were evaluating Panama purely on financial metrics. Others were considering the country’s residency options, including the Qualified Investor Visa, which grants permanent residency tied to a qualifying property purchase – a threshold currently set at $300,000 that is scheduled to rise to $500,000 in October 2026. Still others were drawn by lifestyle considerations, including a digital nomad in the group who was looking to establish Panama as a home base.

The diversity of objectives within a single investor group reflects something true about Panama as a market at this stage: it is broad enough to serve meaningfully different buyer profiles without being so mature that entry points have narrowed significantly.

The Third Summit

CHORD Real Estate has announced the third annual Invest Panama Summit for January 21 through January 24, 2027, in Panama City. The four-day program includes guided tours across Panama City’s primary development zones and an excursion to the Pacific coast. Steve and Ashley Luther are available to speak with prospective participants ahead of the event. Information is available at chordrealestate.com/investpanamasummit, or by contacting CHORD directly at info@chordrealestate.com or (615) 988-1001.

About the Expert: Steve Luther is the Principal, Chief Strategist & Advisor of CHORD Real Estate, a Nashville-based firm specializing in residential and international property services, with an international division focused on Panama and other emerging markets.

Disclaimer: This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views expressed reflect those of the individuals quoted. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.