US Business News

G20 AI Regulation Debate Tests U.S. Light-Touch Strategy
The G20 AI Regulation Debate is moving into sharper focus at the September 1–2 Innovation Ministerial in Chapel Hill, North Carolina. U.S. officials are pressing for a lighter regulatory approach as Europe enforces broader AI obligations and financial regulators warn about cyber risk, creating a direct test of how far major economies can align.

Key Takeaways

  • The G20 Innovation Ministerial is being held September 1–2, 2026, at the Carolina Inn in Chapel Hill, North Carolina.
  • U.S. officials are promoting the nonbinding Carolina Principles, which favor using existing rules for familiar issues while limiting new AI-specific requirements.
  • European Commission enforcement powers covering general-purpose AI obligations became applicable on August 2, 2026.
  • The Financial Stability Board warned on August 31 that frontier AI could materially change the speed, scale and economics of cyber risk.
  • OpenAI CEO Sam Altman and Nvidia CEO Jensen Huang are scheduled to participate in the ministerial.

The G20 AI Regulation Debate has moved beyond broad statements about responsible artificial intelligence. As the Innovation Ministerial opened September 1, U.S. officials began pressing major economies to consider an approach that would keep new AI-specific rules relatively narrow while relying on existing laws and regulators for established risks.

That position is being tested against a global policy landscape that is already diverging. Europe is enforcing detailed obligations for general-purpose AI providers, financial regulators are focusing on cyber resilience, and U.S. agencies are pursuing a mix of lighter national standards and targeted security measures.

G20 AI Regulation Debate Tests the Carolina Principles

The U.S. Commerce Department and the White House Office of Science and Technology Policy are co-hosting the two-day ministerial at the Carolina Inn. Commerce Secretary Howard Lutnick and White House science and technology policy director Michael Kratsios are appearing alongside commerce and technology ministers from G20 members.

Reuters reported that Kratsios planned to ask participants to support the Carolina Principles, a nonbinding framework that would “reserve new regulation for novel considerations.” The approach would encourage governments to use existing regulatory structures when those structures already address the underlying issue.

That message is consistent with the current U.S. federal approach. A December 2025 White House order called for a minimally burdensome national AI framework and sought greater consistency across state rules. A June 2, 2026 executive order directed federal agencies to strengthen AI-related cybersecurity while expressly stating that it did not authorize mandatory licensing, preclearance or permitting for the development or release of AI models.

The domestic policy picture is not entirely hands-off. A federal AI incident reporting proposal introduced in June would require certain advanced-model developers to report specified incidents to the Commerce Department. Government records show H.R. 9477 was introduced on June 25 and referred to the House Committee on Energy and Commerce.

Commerce has also signaled separate AI and semiconductor rulemaking involving export controls. Those measures sit outside the Carolina Principles but illustrate how the U.S. approach can combine fewer broad AI-specific requirements with narrower controls in areas involving security, chips and cross-border technology access.

The ministerial is also bringing technology executives directly into the discussion. OpenAI CEO Sam Altman and Nvidia CEO Jensen Huang are scheduled to participate, while Elon Musk is expected to address attendees virtually. Their participation puts model development, computing infrastructure and commercial deployment alongside the regulatory debate.

Europe’s AI Rules Sharpen the Regulatory Contrast

The European Union provides the clearest regulatory contrast because its AI Act already imposes specific duties on providers of general-purpose AI models. Those requirements include technical documentation, a copyright compliance policy and a public summary describing content used for model training.

Providers of models classified as presenting systemic risk face additional requirements. These include model evaluations, risk assessment and mitigation, serious-incident reporting and cybersecurity protections.

The timing is significant. European Commission enforcement powers covering general-purpose AI obligations became applicable on August 2, 2026. Models placed on the European market before August 2, 2025, generally have until August 2, 2027, to meet the relevant obligations.

That creates a practical issue for U.S. companies operating across multiple markets. A developer may face one regulatory framework in the United States, the EU AI Act in Europe and additional requirements in other jurisdictions.

The difference is not simply a choice between regulation and no regulation. The United States continues to use sector-specific laws, agency authorities, cybersecurity directives and targeted legislative proposals. Europe has added a horizontal AI framework that places specific obligations directly on certain AI providers.

For companies, the central issue is how those requirements affect compliance systems. Different jurisdictions can require separate documentation, testing, reporting processes and internal controls even when the underlying model is the same.

Greater regulatory alignment could reduce duplicated compliance work. Wider divergence could make model releases and cross-border operations more complicated, particularly for companies serving customers in both the United States and Europe.

Cyber Risk Expands the Global AI Policy Debate

The Financial Stability Board added another dimension just before the Chapel Hill ministerial. In an August 31 letter to G20 finance ministers and central bank governors, FSB Chair Andrew Bailey wrote, “For the financial system, the most immediate concern is the potential impact of frontier AI on cyber risk.”

The FSB said frontier models could materially alter the speed, scale and economics of cyber threats. It called for authorities to support safe and responsible model release and deployment, while financial institutions strengthen response and recovery capabilities and the resilience of critical third-party providers.
G20 AI Regulation Debate Tests U.S. Light-Touch Strategy

Photo Credit: Unsplash.com

The warning broadens the debate beyond technology developers. Banks, infrastructure operators and other regulated organizations may increasingly have to account for advanced AI capabilities through existing cybersecurity, operational resilience and risk-management frameworks.

It also exposes the central tension behind the Carolina Principles. U.S. officials are arguing that governments should avoid creating new regulatory structures when existing laws can address familiar problems. The European framework places more explicit obligations on AI providers, particularly when models meet general-purpose or systemic-risk criteria.

Neither approach removes oversight entirely. The policy difference centers on where regulatory responsibility should sit, which requirements should apply directly to model developers, and when governments should create rules specifically for artificial intelligence.

For U.S. technology companies, that distinction has consequences beyond the Chapel Hill meeting. Rules governing model documentation, cybersecurity, incident reporting and market access can influence how companies structure product launches and compliance operations across jurisdictions.

The G20 AI Regulation Debate therefore centers less on whether artificial intelligence should be governed than on how that oversight should be organized. The current discussions are testing whether major economies can narrow practical differences around transparency, cyber resilience and model oversight without creating a single global regulatory system.

Frequently Asked Questions

What is the G20 AI Regulation Debate?

The G20 AI Regulation Debate concerns how major economies should govern artificial intelligence while addressing areas such as safety, cybersecurity, transparency and commercial deployment. The current discussion in Chapel Hill highlights differences between the U.S. preference for narrower AI-specific rules and more prescriptive frameworks such as the EU AI Act.

What are the Carolina Principles?

The Carolina Principles are a nonbinding policy framework being promoted by U.S. officials during the G20 Innovation Ministerial. Reuters reported that the framework encourages governments to reserve new regulation for novel issues and rely on existing regulatory structures where appropriate.

How does the European Union regulate general-purpose AI?

The EU AI Act requires providers of general-purpose AI models to meet obligations involving documentation, copyright compliance and summaries of training content. Providers of models with systemic risk face additional requirements involving evaluations, risk mitigation, incident reporting and cybersecurity.

Why is cyber risk part of the G20 discussion?

The Financial Stability Board has warned that frontier AI could alter the speed, scale and economics of cyber threats. It has called for stronger resilience among financial institutions and critical technology providers while supporting safe model deployment.
SK hynix Breaks Ground on $4B Indiana AI Memory Facility

SK hynix has begun construction of a more than $4 billion semiconductor facility in West Lafayette, Indiana, dedicated to advanced packaging of high-bandwidth memory for AI applications. The project will add U.S. production capacity, support semiconductor research and create thousands of direct and indirect jobs in the region.

Key Takeaways

  • SK hynix broke ground on its Indiana semiconductor facility on August 27, 2026.
  • The company is investing more than $4 billion in the West Lafayette project.
  • The facility will focus on advanced packaging of high-bandwidth memory for AI applications.
  • Mass production is planned for the second half of 2029.
  • The project is expected to support approximately 7,000 direct and indirect jobs.

SK hynix Begins Construction in West Lafayette

SK hynix Indiana operations are expanding with construction of a new semiconductor facility in West Lafayette, Indiana. The company broke ground on the project on August 27, 2026, beginning development of a facility centered on advanced packaging for high-bandwidth memory used in AI applications.

The project represents an investment of more than $4 billion by SK hynix. The scale of the investment places the Indiana facility among the company’s major U.S. semiconductor projects and gives the company additional production capacity within the country.

The facility is being developed in West Lafayette, establishing an advanced semiconductor operation in Indiana. Its planned activities will center on high-bandwidth memory, commonly referred to as HBM, and the packaging processes required for those memory products.

The project follows other U.S. efforts to expand domestic semiconductor production, including new U.S. chip manufacturing initiatives involving advanced semiconductor capacity and related manufacturing infrastructure.

SK hynix has identified AI applications as a key use for the memory that will be handled at the Indiana facility. HBM is used in systems that require high-speed memory capabilities, making the planned operation directly connected to the production of memory products for AI-related computing.

Construction is scheduled to precede the facility’s production phase by several years. SK hynix plans to begin mass production at the Indiana site during the second half of 2029.

The project also has a workforce component. SK hynix expects the development to support approximately 7,000 direct and indirect jobs, adding employment connected to the facility and related activity in the region.

The combination of capital investment, semiconductor production capacity and employment makes the Indiana project a major U.S. expansion for SK hynix.

Indiana Facility Targets Advanced AI Memory Packaging

The Indiana semiconductor facility is designed around advanced packaging of high-bandwidth memory rather than simply adding conventional semiconductor capacity.

Advanced packaging is the stage in semiconductor production that prepares memory and other chip components for use in computing systems. For SK hynix, the Indiana operation will apply that capability to HBM products intended for AI applications.

The facility will add U.S. production capacity for SK hynix. That capacity will allow the company to perform advanced semiconductor operations in Indiana as part of its broader business.

The planned production schedule also provides a clear development timeline. Construction begins in 2026, while mass production is targeted for the second half of 2029. The multiyear period between groundbreaking and production allows the facility to move through construction and preparation before commercial output begins.

SK hynix’s investment exceeds $4 billion, giving the project a substantial capital commitment. The spending is directed toward the Indiana facility and its advanced semiconductor operations.

The project is also tied specifically to AI memory chips. SK hynix’s decision to dedicate the facility to advanced HBM packaging connects the Indiana operation to the company’s work in memory products designed for AI computing applications.

A separate U.S. memory investment announced by Micron also includes research into memory technologies and advanced packaging, providing a comparable example of U.S. AI memory investment involving semiconductor research and development.

For U.S. businesses involved in semiconductor production and related services, the facility adds another location for advanced memory operations. The project also creates demand for workers and supporting business activity associated with a large semiconductor facility.

Mass Production Is Planned for 2029

SK hynix plans to begin mass production at the Indiana facility in the second half of 2029. The target establishes the next major stage of the project after the August 2026 groundbreaking.

The production schedule means the facility will spend several years moving from construction to operational readiness. The company has identified 2029 as the point at which the Indiana site is expected to enter mass production.

SK hynix Breaks Ground on $4B Indiana AI Memory Facility

Photo Credit: Unsplash.com

The planned output will involve high-bandwidth memory packaging for AI applications. That production focus remains central to the facility’s purpose and distinguishes the project from a general-purpose manufacturing site.

The timing also provides a defined framework for the project’s development. Groundbreaking took place in August 2026, while the targeted production period begins more than three years later.

SK hynix expects the Indiana project to support approximately 7,000 direct and indirect jobs. The figure covers employment connected directly and indirectly to the project, extending beyond positions located inside the facility itself.

The employment impact gives the project significance for the West Lafayette area as construction and associated business activity develop. The jobs figure also reflects the broader workforce requirements connected to the semiconductor facility.

Mass production will be the operational stage at which the investment begins supporting the facility’s planned memory-packaging activities. Until then, the project will remain focused on construction and development.

The 2029 production target is therefore a key date for the project. It provides businesses, workers and other organizations connected to the development with a defined timeline for the facility’s planned transition into production.

Project Includes Semiconductor Research and Development

The Indiana project includes semiconductor research and development as part of the facility’s planned activities. SK hynix is incorporating research capabilities alongside advanced packaging operations at the West Lafayette site.

The research component gives the facility a role beyond production. The project is intended to support semiconductor research connected to the technologies used in advanced memory packaging.

SK hynix is also working with Purdue University on semiconductor research and development associated with the project. The relationship connects the company’s Indiana operations with research activity based in the state.

The combination of manufacturing and research creates two distinct functions within the project. The facility will support planned production of high-bandwidth memory while also contributing to semiconductor research and development.

That structure gives the Indiana site a broader operational purpose within SK hynix’s U.S. activities. Production capacity and research capabilities are both included in the company’s plans for the project.

The research component is also directly connected to the type of technology being developed at the facility. High-bandwidth memory packaging requires advanced semiconductor processes, making research relevant to the facility’s stated production focus.

Purdue University’s involvement adds an academic institution to the project. The partnership places semiconductor research and development alongside the commercial operations planned by SK hynix.

The research activities form part of the broader investment in West Lafayette rather than serving as a separate project. SK hynix’s more than $4 billion commitment covers the Indiana development centered on advanced semiconductor packaging and related capabilities.

Investment Expands SK hynix’s U.S. Operations

The Indiana project expands SK hynix’s semiconductor operations in the United States through a more than $4 billion investment in advanced memory packaging.

The company’s planned U.S. capacity will focus on high-bandwidth memory for AI applications. That specialization gives the Indiana facility a defined role within SK hynix’s operations and links the project directly to AI memory production.

The project also establishes a substantial long-term commitment to West Lafayette. Construction began in August 2026, with mass production scheduled for the second half of 2029 and approximately 7,000 direct and indirect jobs expected to be supported.

The investment combines several business functions at one Indiana location. Advanced semiconductor packaging, AI memory production, research and development, and employment are all included in the project’s stated plans.

The facility’s U.S. location also gives SK hynix an additional operating base for its semiconductor business. The project therefore expands the company’s physical presence and production capabilities in the country.

Other U.S. semiconductor manufacturers are also increasing capacity linked to artificial intelligence and data centers. Intel, for example, has reported expanded AI infrastructure plans tied to manufacturing capacity and enterprise demand for data center processors.

The Indiana investment is also part of a manufacturing environment in which U.S. businesses are increasing spending on computers, electronics and related equipment. Recent capital-goods data showed stronger orders for computers and electronic products, providing additional context for investment across technology-related manufacturing.

For SK hynix, the Indiana facility provides a dedicated location for advanced memory packaging and related research. Its planned production schedule extends through 2029, while the project’s employment and investment commitments establish its expected scale.

The development will therefore proceed from construction into research, preparation and eventual mass production, with high-bandwidth memory for AI applications remaining the central focus of the Indiana operation.

Frequently Asked Questions

What is SK hynix building in Indiana?

SK hynix is building an advanced semiconductor packaging facility in West Lafayette, Indiana. The facility will focus on high-bandwidth memory for AI applications.

How much is SK hynix investing in Indiana?

SK hynix is investing more than $4 billion in the Indiana project. The investment covers the development of the advanced semiconductor facility.

When will the Indiana facility begin production?

SK hynix plans to begin mass production at the facility during the second half of 2029. The project broke ground on August 27, 2026.

How many jobs will the SK hynix Indiana project create?

The project is expected to support approximately 7,000 direct and indirect jobs. The figure includes employment connected to the facility and related project activity.

What type of memory will the Indiana facility produce?

The facility will focus on high-bandwidth memory, or HBM, for AI applications. Its operations will center on advanced packaging of those memory products.

SpaceX Plans $100B Starship Complex in Louisiana

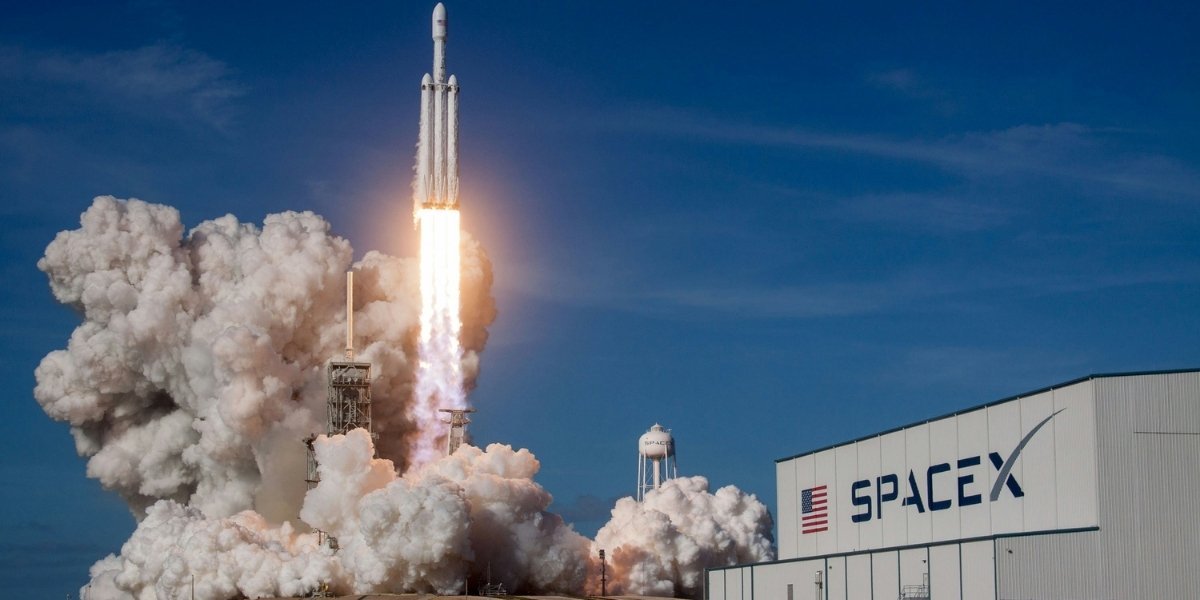
SpaceX plans to build a $100 billion Starship launch complex in southern Louisiana, adding major aerospace infrastructure to the state. The project is expected to include launch facilities and support infrastructure while creating thousands of direct and indirect jobs in the region.

Key Takeaways

  • SpaceX plans to invest $100 billion in a Starship complex in southern Louisiana.
  • The facility will occupy a 125,000-acre site on Pecan Island in Vermilion Parish.
  • SpaceX expects the project to create more than 3,000 direct jobs over 10 years.
  • Louisiana Economic Development estimates more than 8,100 additional indirect jobs.
  • Construction is expected to begin by the end of 2027, with initial operations targeted for 2030.

SpaceX Announces $100 Billion Louisiana Starship Complex

SpaceX plans to invest $100 billion to develop a new Starship launch complex in southern Louisiana, expanding its launch infrastructure beyond its existing South Texas operations and planned Florida facilities. The company named the proposed site Starbase Louisiana and plans to use it for Starship launches and related operations. 

The facility will be built on a 125,000-acre site at Pecan Island in Vermilion Parish. Louisiana Economic Development said the campus is designed to support thousands of launches annually when fully developed.

SpaceX President and Chief Operating Officer Gwynne Shotwell said the facility will eventually support a high-frequency Starship launch operation. The company’s plans include infrastructure for producing and handling rocket propellant, generating power, processing vehicles and moving equipment by water.

The Louisiana project adds another U.S. location to SpaceX’s Starship launch plans. The company’s existing Starbase facility is in South Texas, while another launch facility is planned in Florida. The Louisiana complex is intended to expand the company’s capacity for Starship operations.

The proposed investment also represents a major private-sector construction project for Louisiana. State officials said the development is expected to generate direct employment at SpaceX as well as additional jobs among contractors, suppliers and other businesses connected to the project.

Starship Launch Infrastructure Planned for Vermilion Parish

The Starbase Louisiana site will cover roughly 125,000 acres along the Louisiana coast. SpaceX selected the Pecan Island location for a large-scale launch complex capable of accommodating multiple launch facilities and supporting infrastructure.

Louisiana Economic Development said the completed campus is expected to include five launch complexes, each with two launch pads. The site is also planned to include propellant farms, a propellant production facility, power infrastructure, vehicle processing facilities and employee housing.

The facility’s design is intended to support a large number of Starship launches. SpaceX said the site will eventually be capable of supporting thousands of launches each year, making launch frequency a central feature of the planned complex.

The location also provides SpaceX with access to Gulf Coast transportation infrastructure. Plans released by the company include deep-water shipping capabilities for the campus, along with facilities for processing and handling vehicles and materials.

Propellant infrastructure will form another major part of the site. The proposed campus includes facilities for producing and storing rocket propellant, as well as power-generation infrastructure needed to support operations.

The scale of the planned facility distinguishes it from a launch pad alone. The project is structured as a broader campus combining launch operations with manufacturing, logistics, power and other supporting functions.

Planned Launch and Support Infrastructure

The planned infrastructure is intended to allow SpaceX to handle multiple stages of Starship operations at one location. Vehicle processing, propellant production, launch facilities and transportation infrastructure are all included in the development plans.

SpaceX’s Starship system is being developed for reusable spaceflight operations. The Louisiana complex is intended to provide additional capacity as the company expands its planned Starship launch operations in the United States.

Project Includes Launch, Propellant and Power Facilities

SpaceX’s Louisiana plans extend beyond launch infrastructure to include systems needed to support recurring operations. The planned campus will have propellant production and storage facilities, power-generation capacity and vehicle-processing areas.

The company also plans deep-water shipping infrastructure at the site. That facility is intended to support the movement of equipment and materials required for the large launch operation. An airport is also included in SpaceX’s plans for the self-contained campus.

The planned complex will include employee housing as part of its infrastructure. Louisiana Economic Development lists housing among the facilities expected at full buildout, alongside launch pads, propellant facilities and vehicle-processing operations.

SpaceX expects the Louisiana facility to support Starship launches as well as satellite-related operations. The company’s plans include using Starship for future satellite deployment activities, including its broader satellite ambitions.

The Louisiana project is part of a larger commercial space infrastructure environment that includes companies developing systems for lunar construction and other space-based operations. A recent commercial aerospace partnership, for example, paired lunar construction technology with remotely operated robotics for planned activities on the Moon. 

SpaceX’s plans call for the Louisiana location to become its largest launch facility. At full buildout, the site is expected to contain 10 launch pads across five launch complexes, in addition to its propellant, power, processing and housing facilities.

The combination of launch pads, propellant systems, power generation, vehicle processing and shipping infrastructure means the project will require multiple types of construction and industrial work. Those requirements form a substantial portion of the project’s expected economic activity.

SpaceX Expansion Expected to Create Thousands of Jobs

SpaceX expects the Louisiana project to create more than 3,000 direct jobs during the next decade. Louisiana Economic Development said those positions are expected to have an average annual salary of $92,600.

The state agency estimates that the project will generate more than 8,100 additional indirect jobs. Combined with the direct positions, the estimate exceeds 11,100 new job opportunities connected to the development in the Acadiana region.

The employment impact extends beyond SpaceX’s own workforce. The project will require contractors and suppliers for construction, infrastructure, equipment, transportation and other services associated with the campus. Louisiana Economic Development said the company has joined Source Louisiana, providing a pathway for Louisiana suppliers, contractors and service providers to compete for project-related work.

The project also includes an economic agreement with local governments. Louisiana Economic Development said the payment-in-lieu-of-taxes agreement provides a $20 million upfront payment and at least $25 million annually for 25 years, resulting in more than $645 million in direct local payments over the agreement’s duration.

The project is expected to create additional employment during construction before the permanent operating workforce is established. Louisiana Economic Development estimates peak construction employment at 34,516 jobs.

The combination of direct employment, construction work and supplier activity gives the Louisiana project an economic footprint beyond the personnel SpaceX will directly employ. The state expects contractors and vendors across the region to participate in the development.

Expected Employment and Regional Economic Activity

SpaceX Plans $100B Starship Complex in Louisiana

Photo Credit: Unsplash.com

The direct jobs are expected to be created over a 10-year period, while the project’s construction phase will require a separate workforce. The state has also identified supplier and contractor participation as part of the economic activity associated with the development.

The project therefore links aerospace operations with construction, manufacturing, logistics, professional services and other business activity required to build and operate the campus.

SpaceX’s wider infrastructure plans also include projects connected to computing and satellite systems. Intel’s participation in a Musk-led semiconductor manufacturing project in Texas, for example, includes planned chip production for applications tied to SpaceX and space-based computing.

Construction and Operations Timeline Extends Into 2030

Construction of the Louisiana Starbase complex is expected to begin by the end of 2027, according to Louisiana Economic Development. The state agency expects initial operations to come online in 2030.

SpaceX has separately said the first Starship launch from the Louisiana site is targeted for 2029. The launch target precedes the state’s broader initial-operations timeline for the full facility.

The schedule places several stages of development between the announcement and full operations. Construction must establish the launch complexes, propellant systems, power infrastructure, vehicle-processing facilities and other parts of the campus before the site reaches its planned operating capacity.

The project is expected to be developed in phases as the infrastructure is built. Louisiana Economic Development’s project information identifies the end of 2027 as the construction start target and 2030 as the expected date for initial operations.

The proposed facility will also require the development of transportation and utility infrastructure. The planned campus includes deep-water shipping capabilities, power generation and other systems intended to support its operations independently.

SpaceX’s plans call for the Louisiana location to become its largest launch facility. At full buildout, the site is expected to contain 10 launch pads across five launch complexes, in addition to its propellant, power, processing and housing facilities.

The Louisiana project will add capacity to SpaceX’s U.S. Starship operations while construction proceeds through the end of the decade. Its planned launch activity, workforce and supporting infrastructure will depend on completion of the campus and the systems required for Starship operations.

SpaceX’s planned launch infrastructure also sits within a larger U.S. commercial space market that includes satellite connectivity. Amazon’s acquisition of Globalstar has added another major corporate investment in satellite communications, with the deal positioning Amazon to compete more directly with SpaceX’s Starlink business.

Frequently Asked Questions

How much will SpaceX’s Louisiana Starship complex cost?

SpaceX plans to invest $100 billion in the Louisiana Starbase project. The investment covers development of the launch complex and its supporting infrastructure.

Where will SpaceX build the Louisiana Starship complex?

The complex will be built on a 125,000-acre site at Pecan Island in Vermilion Parish, Louisiana. The company has named the planned facility Starbase Louisiana.

How many jobs is the SpaceX Louisiana project expected to create?

SpaceX expects to create more than 3,000 direct jobs over 10 years. Louisiana Economic Development estimates the project will generate more than 8,100 additional indirect jobs, bringing the total to more than 11,100 new job opportunities.

When is construction of the SpaceX Louisiana complex expected to begin?

Louisiana Economic Development expects construction to begin by the end of 2027. SpaceX has separately targeted 2029 for the first Starship launch from the site.

When is the Louisiana Starship complex expected to begin operations?

Louisiana Economic Development expects initial operations to come online in 2030. The timeline refers to initial operations of the broader facility, while SpaceX has identified 2029 as the target for the first Starship launch.

Micron Research Labs Puts $10 Billion Behind U.S. AI Memory Push

Micron Research Labs is launching in Boise, Idaho, with Micron Technology planning to direct $10 billion to the research institution over the next decade. The initiative will focus on memory, computing architectures, packaging and future chip manufacturing, providing a clearer view of how Micron is expanding long-horizon research as AI infrastructure demand increases.

Key Takeaways

  • Micron Technology announced Micron Research Labs on August 20, 2026, with Boise serving as its headquarters.
  • The company plans to direct $10 billion to the research initiative over the next decade.
  • Micron expects to break ground on the flagship Boise facility in calendar 2027.
  • Research will cover memory technologies, computing architectures, advanced packaging and future semiconductor manufacturing.
  • The program is separate from Micron’s previously announced U.S. manufacturing and research expansion.

Micron Research Labs places a new research institution alongside the company’s existing technology operations at a time when artificial intelligence systems are increasing demand for faster memory and data movement.

Micron said the Boise-based program will connect its researchers with universities, customers, startups and other semiconductor-sector partners. The planned flagship facility is expected to accommodate hundreds of researchers and serve as part of a broader network that includes university collaborations and global satellite labs.

The distinction between the new institution and Micron’s existing production expansion is significant. The company describes Micron Research Labs as a long-horizon program focused on technologies beyond current product roadmaps rather than simply an extension of near-term manufacturing capacity.

Micron Research Labs Targets Long-Horizon Chip Research

Micron Research Labs will focus on several areas that increasingly overlap in advanced computing systems. They include critical memory technologies, advanced memory and computing architectures, packaging and future semiconductor manufacturing methods.

The research agenda reflects the growing complexity of AI hardware. High-performance processors depend not only on computing capability but also on memory bandwidth, packaging and the speed at which large volumes of data can move between components.

Scott DeBoer, Micron’s executive vice president and chief technology and products officer, described the initiative as supporting “the kind of research that sits upstream of every product we build.”

Micron said the institution will look beyond a 10-year research horizon. That structure is intended to give researchers room to examine concepts that may not yet be ready for commercial production while maintaining connections with the company’s technical operations across the United States, Europe, Japan, India, Singapore and Taiwan.

The $10 billion plan will also support university collaborations and partnerships across the semiconductor ecosystem. Chip development increasingly requires coordination across equipment, materials, memory architecture, packaging and production processes, particularly as AI systems place greater demands on hardware performance.

The new research institution creates a dedicated setting for those longer-term projects rather than tying every research effort directly to an existing product cycle.

AI Memory Demand Raises the Stakes for Micron

The announcement follows a sharp increase in Micron’s reported financial results. For fiscal third-quarter 2026, the company reported revenue of $41.46 billion, compared with $9.30 billion during the same quarter a year earlier.

Micron’s cloud memory business generated $13.77 billion during the quarter, while its core data center business reported $11.52 billion. Those figures place data center operations at the center of Micron’s recent growth as demand for AI infrastructure increases the need for memory and storage products.

High-bandwidth memory, commonly known as HBM, has become especially relevant to AI systems because it can provide the rapid data movement required by advanced accelerators. Micron competes in that market alongside major memory manufacturers including Samsung Electronics and SK Hynix.

The broader semiconductor industry is responding to similar demand. Intel AI infrastructure plans have focused on increased computing capacity as enterprise AI workloads expand, while other chip manufacturers are reporting greater exposure to data center demand.

For Micron, that environment increases the importance of research that reaches beyond one existing memory product. The new lab is expected to examine how memory, computing architectures and manufacturing technologies may need to change as AI systems become more complex.

The memory sector has also historically experienced periods of changing supply, demand and pricing. A wider research mandate does not eliminate those market conditions, but it gives Micron a platform for technical work that can extend across multiple product generations.

Boise Takes a Larger Role in Micron’s U.S. Chip Footprint

Micron Research Labs Puts $10 Billion Behind U.S. AI Memory Push

Photo Credit: Unsplash.com

Boise already serves as Micron’s headquarters and one of its major research centers. The planned Micron Research Labs campus would deepen that role by placing a dedicated long-term research institution near the company’s existing technical and manufacturing operations.

Micron expects to break ground on the facility in calendar 2027. The company said the site will be designed to accommodate hundreds of researchers and host research conferences, workshops and technical forums.

The lab will sit alongside a wider U.S. expansion that Micron says will exceed $250 billion in manufacturing and research spending through 2035. That broader program includes operations and projects in Idaho, New York and Virginia and is separate from the $10 billion planned for Micron Research Labs.

Micron is already constructing a leading-edge memory fabrication facility in Boise, where meaningful DRAM output is projected for 2027. The company also broke ground on its Clay, New York, manufacturing complex in January 2026 and reached its first concrete-pour milestone in July.

The expansion comes as data center semiconductor demand is becoming more visible across the chip sector, extending beyond processors to memory, connectivity and supporting components.

Locating long-horizon research near manufacturing expertise could allow Micron to connect early technical work with knowledge gained from semiconductor production while preserving the lab’s broader mandate.

Micron Research Labs therefore adds a distinct research layer to the company’s U.S. semiconductor operations. Its longer-term relevance will depend on the technologies produced through the research network, how those concepts progress toward practical applications and how computing requirements develop over the coming decade.

Frequently Asked Questions

What is Micron Research Labs?

Micron Research Labs is a Boise-based research institution announced by Micron Technology on August 20, 2026. It is intended to pursue long-horizon research involving memory, computing architectures, packaging and future semiconductor manufacturing.

How much does Micron plan to direct to the research program?

Micron said it plans to direct $10 billion to the initiative over the next decade. The planned amount is separate from the company’s previously announced U.S. manufacturing and research expansion.

When will the Boise facility break ground?

Micron expects to break ground on the flagship facility in calendar 2027. The company says the campus is being designed to accommodate hundreds of researchers.

Why is memory important for AI infrastructure?

AI accelerators process large volumes of data and rely on memory systems capable of transferring information quickly. High-bandwidth memory is one technology used to meet those requirements in advanced AI computing systems.

How does Micron Research Labs fit into Micron’s U.S. operations?

Micron Research Labs adds a dedicated long-term research component to the company’s existing U.S. footprint. Micron also has major manufacturing and research operations planned or underway in Idaho, New York and Virginia.

U.S. Data Center Financing Faces Closer Lender Scrutiny

Banks and asset managers are applying greater scrutiny to U.S. data center projects as community opposition and permitting concerns affect financing assessments. Major lenders including JPMorgan, Morgan Stanley and Bank of America remain active in the sector while examining project readiness, approvals and local support as part of credit-risk reviews.

Key Takeaways

  • Lenders are incorporating community support and permitting status into data center credit assessments.
  • JPMorgan, Morgan Stanley and Bank of America continue to finance and advise on data center projects.
  • At least 75 U.S. data center projects worth about $130 billion faced local opposition during the first quarter of 2026, according to Data Center Watch.
  • Banks conduct technical, environmental, zoning, appraisal and insurance reviews before funding projects.
  • Financing agreements can require projects to maintain permits, approvals and compliance throughout construction.

U.S. data center financing is receiving closer scrutiny from banks and asset managers as lenders assess whether projects can secure the approvals and community support required to proceed. The financing review now includes factors beyond the technical and financial characteristics of a proposed facility.

Karen Fang, global head of infrastructure and sustainable finance at Bank of America, said project readiness includes required permitting and approvals as well as community support from people living near a proposed facility. Credit quality remains another central consideration for lenders.

The additional review is relevant because data centers require substantial capital and can take significant time to develop. A financing commitment can therefore expose lenders to delays if a project encounters permitting problems, local resistance or other obstacles before construction is completed.

JPMorgan, Morgan Stanley and Bank of America remain active in the sector. Their involvement reflects continued lender participation in data center development even as financial institutions assess projects more selectively.

Community concerns cited in the financing review include noise, visual impact, electricity consumption and water use. These issues can become part of the assessment surrounding whether a proposed facility has sufficient local support to advance through its approval process.

The infrastructure requirements behind these facilities also have implications for businesses that depend on regional power systems. AI data center electricity costs have become a relevant consideration for manufacturers operating in areas where data center demand places additional pressure on electricity resources.

Permits and Project Readiness Shape Financing Decisions

Permitting has become a central condition for data center project financing because lenders need confidence that construction can legally proceed and remain compliant during development.

Banks conduct extensive due diligence before committing capital. The review can include technical assessments, environmental reviews, zoning analysis, property appraisals and insurance evaluations. These checks are used alongside traditional assessments of the project’s financial strength and the parties involved.

For data center developers, obtaining financing therefore involves more than demonstrating demand for computing capacity. A project must also progress through the relevant approval processes and satisfy requirements established by local authorities and financing partners.

The financing process can continue after a loan agreement is signed. Construction funding may be released through separate drawdowns, with borrowers required to demonstrate compliance with agreed financial covenants and monitoring requirements before additional funds are provided.

Kevin Curtin, head of AI infrastructure investment banking at JPMorgan, said the work required to establish a bank loan for these projects is significant. He also noted that lender oversight continues throughout construction.

That structure places project execution alongside initial underwriting. A development that encounters approval delays after financing has been arranged can create additional work for lenders and developers, particularly when construction schedules and capital deployment depend on regulatory milestones.

Resource requirements can also affect the assessment of proposed facilities. Data center power and water use has become an important consideration for companies and communities evaluating large-scale data center development.

Local Opposition Creates Risks for Major Data Center Projects

Local opposition has affected a significant number of proposed U.S. data center developments. Data Center Watch reported that at least 75 projects valued at approximately $130 billion were blocked or delayed during the first quarter of 2026. The projects represented developments facing resistance between January and March.

The reported opposition has included concerns over electricity demand, water consumption, noise and the physical appearance of large facilities. These issues can affect the approval process and create uncertainty around construction schedules.

For lenders, delays can create a direct financing concern because capital commitments are tied to projects that must reach specified development milestones. A project that does not secure necessary approvals may require additional review or changes to its financing arrangements.

Reuters reported that some projects involving major technology companies have encountered resistance while still progressing through financing. The report also cited a data center project in Virginia that was terminated after local pushback.

The geographic distribution of projects also matters to lenders. Banking executives indicated that financial institutions are paying attention to states and communities that are more receptive to data center construction.

This does not mean lenders have withdrawn from the sector. Instead, community acceptance has become one of several project characteristics considered during due diligence.

The scale of reported opposition gives lenders a concrete reason to examine local conditions before financing. For developers, the approval process can therefore affect not only construction schedules but also the conditions attached to external capital.

Banks Maintain Financing Activity Across U.S. Data Centers

U.S. Data Center Financing Faces Closer Lender Scrutiny

Photo Credit: Unsplash.com

Despite the additional scrutiny, major financial institutions continue to participate in U.S. data center financing. JPMorgan, Morgan Stanley and Bank of America are among the Wall Street firms advising clients and arranging capital for projects in the sector.

Morgan Stanley Chief Financial Officer Sharon Yeshaya said the firm is aware of the risks associated with the sector’s capital requirements and remains involved in helping clients raise, syndicate and underwrite financing.

The continued participation of major banks indicates that project financing remains available for developments that satisfy lenders’ requirements. At the same time, the underwriting process can differ depending on a project’s permits, location, technical characteristics and credit quality.

Data centers are used for cloud storage and artificial intelligence computing, making their development dependent on substantial physical infrastructure. That infrastructure can include buildings, electrical systems, cooling equipment and other specialized facilities.

For lenders, these characteristics create a financing profile that requires technical and environmental review alongside conventional financial analysis. The projects can also require substantial capital over extended construction periods.

Community approval adds another consideration to the financing process. A technically viable project can still face delays if local authorities do not approve necessary permits or if community resistance affects the development schedule.

Financial institutions are therefore evaluating both the underlying project and the conditions surrounding its construction. The approach allows lenders to identify potential obstacles before committing capital and to establish requirements for continued financing during construction.

The financing considerations also extend to companies producing components required by data center infrastructure. U.S. chip manufacturing support expands provides context on semiconductor manufacturing capacity supporting computing infrastructure and other technology-dependent industries.

Financing Agreements Address Construction and Cancellation Risks

Data center financing agreements can include conditions designed to protect lenders if a project encounters delays, loses required approvals or fails to meet agreed development standards.

Construction drawdowns can depend on continued compliance with financial covenants and monitoring requirements. This means borrowers may need to demonstrate that the project remains within the conditions established when the financing was arranged before receiving additional capital.

Permits and approvals are particularly important because they determine whether construction can proceed. A project without the required authorizations may not be able to meet the milestones attached to its financing.

Lenders also consider the possibility that a development could be canceled or significantly delayed. The recent increase in projects facing local opposition has made that risk more relevant to due diligence.

The financing review can therefore extend across the entire construction process rather than ending when a loan is initially approved. Technical assessments, environmental requirements, zoning conditions, insurance arrangements and project compliance can remain relevant as construction progresses.

For developers, the structure means financing commitments must be supported by continued execution. For banks, it provides mechanisms for monitoring whether projects remain eligible for additional funding.

The approach also places greater importance on the relationship between developers and local communities before construction begins. Community concerns do not automatically prevent financing, but they can become part of the information lenders use to assess whether a project is ready to proceed.

The reported financing practices show that U.S. data center projects are being evaluated through multiple layers of due diligence, with financial performance, technical feasibility, regulatory approvals and local conditions considered together.

Frequently Asked Questions

How does community opposition affect data center financing?

Community opposition can affect financing assessments by creating uncertainty around permits, approvals and construction schedules. Lenders may examine local support as part of their broader project-risk review.

Which banks finance U.S. data center projects?

JPMorgan, Morgan Stanley and Bank of America are among the major financial institutions involved in advising on and financing U.S. data center projects.

What permits do data center lenders assess?

Lenders assess the permits and approvals required for a project to proceed, alongside zoning, environmental, technical, appraisal and insurance considerations.

How much data center investment faced local opposition?

Data Center Watch reported that at least 75 projects worth approximately $130 billion faced local opposition during the first quarter of 2026.

What risks do lenders assess before financing data centers?

Lenders assess credit quality, project readiness, permitting, technical conditions, environmental issues, zoning, insurance, construction compliance and potential delays.

Intel Expands AI Infrastructure Plans on Enterprise Chip Demand

Intel AI infrastructure plans moved forward after the company announced increased investment in manufacturing capacity and raised its capital spending outlook in response to stronger enterprise demand for data center processors supporting artificial intelligence workloads. The announcement also reaffirmed Intel’s roadmap for its next-generation manufacturing technology and reflected continued investment in semiconductor production.

Key Takeaways

  • Intel increased its capital spending forecast to support AI-related processor demand.
  • Enterprise demand for data center CPUs contributed to expanded infrastructure plans.
  • Intel reaffirmed its roadmap for high-volume production using its 14A manufacturing process.
  • The company reported multi-year customer agreements for data center processors and AI accelerators.
  • Intel said demand for AI computing has influenced its manufacturing investment strategy.

Intel announced expanded investment plans for AI infrastructure after reporting stronger demand for processors used in enterprise data centers. The company increased its capital spending forecast for the current year and confirmed continued investment in manufacturing technologies designed to support future generations of advanced semiconductors.

Company executives said demand for central processing units used in AI-enabled data centers exceeded earlier expectations, prompting Intel to revise its spending plans. The updated outlook reflects additional investment in manufacturing capacity intended to support long-term production requirements for enterprise computing customers.

The company also confirmed progress toward its 14A semiconductor manufacturing process, which remains a central element of Intel’s strategy to produce advanced chips for both internal products and external foundry customers. Executives stated that customer engagement surrounding the manufacturing platform strengthened during the latest quarter.

Intel Expands AI Infrastructure Plans Following Enterprise Demand

Intel said growing enterprise adoption of AI applications has increased demand for processors used in cloud computing and data center environments. Company executives reported that organizations deploying AI workloads continue to require high-performance CPUs alongside specialized AI accelerators to support a broad range of computing tasks. Businesses expanding AI deployments are also evaluating new Google AI chips for enterprise inference as organizations assess computing options for AI workloads.

The company stated that demand has been particularly strong for processors supporting enterprise AI deployments, including workloads involving autonomous software agents and advanced computing applications. Intel reported that orders for certain data center CPUs exceeded available manufacturing capacity during the quarter.

Executives also confirmed that customer demand contributed to the company’s decision to expand investment in production capabilities. Intel said it remains focused on increasing manufacturing output while maintaining its long-term technology roadmap.

The company reported that enterprise customers continue to sign multi-year agreements covering future processor deliveries. These agreements include products intended for data centers and AI computing environments, providing greater visibility into future production requirements.

Capital Spending Outlook Increases for Semiconductor Production

Updated Investment Forecast

Intel increased its projected capital expenditures for the year from $18 billion to $20 billion. Company executives stated that spending is also expected to rise further during the following year as manufacturing projects continue.

The increased investment is intended to support production capacity for processors used in enterprise computing and artificial intelligence workloads. Intel said manufacturing expansion remains aligned with customer commitments and anticipated demand for future products.

Executives stated that the company continues to evaluate investment decisions carefully while maintaining financial discipline. They also noted that long-term customer agreements provide additional confidence when planning manufacturing capacity.

Manufacturing Capacity Priorities

Intel said its investment strategy focuses on expanding semiconductor production capabilities while preparing facilities for future manufacturing technologies. These investments support both Intel-designed products and the company’s contract manufacturing operations. The company’s manufacturing priorities also align with ongoing discussions surrounding U.S. AI semiconductor export rules and their impact on domestic chip production.

The company continues to position its foundry business as an important component of its manufacturing strategy. Executives stated that customer engagement for future production technologies has improved, supporting confidence in planned manufacturing expansion.

Intel also confirmed that production planning considers both current processor demand and future customer commitments. Manufacturing investments are expected to support increasing requirements from enterprise customers deploying AI-enabled computing infrastructure.

Data Center CPU Orders Support Manufacturing Strategy

Multi-Year Customer Agreements

Intel reported that it has secured multi-year agreements with customers purchasing data center processors and AI accelerators. Company executives said these agreements typically extend between three and five years and include commitments covering future product deliveries.

Some agreements include both pricing and volume commitments, while others focus primarily on production volumes. Intel stated that these long-term arrangements assist manufacturing planning by providing greater visibility into customer demand.

The company said enterprise customers continue investing in infrastructure capable of supporting AI computing workloads. These purchasing commitments contribute to Intel’s production planning and capital allocation decisions, reflecting a new frontier for enterprise AI as organizations integrate advanced computing into business operations.

AI Workload Requirements

Intel stated that enterprise AI deployments require substantial computing resources beyond specialized accelerators alone. Central processing units remain responsible for many core computing functions within data center environments, including workload management, system coordination, and application execution.

Executives reported that growing adoption of AI agents has contributed to stronger demand for server processors. These systems support enterprise applications that perform automated tasks requiring continuous processing across large-scale computing environments.

Intel also reported stronger performance in its data center and AI business during the latest quarter, reflecting continued customer demand for enterprise computing products.

Intel Reaffirms 14A Process Roadmap for Future Production

Intel confirmed that development of its 14A manufacturing technology continues according to its planned roadmap. Company executives said recent customer engagement increased confidence in achieving high-volume production using the process beginning in 2028.

The 14A process represents Intel’s next generation of semiconductor manufacturing technology. The company intends to use the platform for future processors while also offering manufacturing services to external customers through its foundry business.

Executives stated that progress during the latest quarter strengthened the company’s commitment to advancing the manufacturing process. Intel said customer interest has improved compared with previous expectations, supporting continued investment in production technology.

The company also indicated that manufacturing development remains an important element of its broader semiconductor strategy. Continued investment in advanced fabrication technologies is intended to strengthen production capabilities for future enterprise computing products.

Enterprise AI Adoption Shapes Long-Term Infrastructure Investment

Demand for Data Center Computing

Intel reported that enterprise customers continue expanding data center infrastructure to support artificial intelligence applications. Organizations deploying AI workloads require computing platforms capable of processing increasing volumes of enterprise data while maintaining system performance.

The company stated that CPUs remain essential components of these environments because they coordinate many computing tasks performed alongside AI accelerators. Enterprise deployments typically combine multiple processor technologies depending on workload requirements.

Intel said the continued expansion of enterprise AI computing has influenced customer purchasing decisions for both processors and supporting infrastructure.

Long-Term Production Planning

Intel stated that future manufacturing decisions will continue to reflect customer demand and long-term production requirements. The company said multi-year agreements and increased enterprise investment in AI computing support continued expansion of manufacturing capacity.

Executives confirmed that production planning includes both internally designed products and semiconductor manufacturing services provided to external customers. The company also reaffirmed its commitment to advancing manufacturing technologies that support future enterprise computing platforms.

Intel’s updated investment plans reflect the company’s focus on expanding production capabilities while meeting growing requirements from organizations deploying AI-powered data center infrastructure. Companies scaling these facilities are also monitoring AI data center electricity costs as power demand becomes an increasingly important operational consideration.

Frequently Asked Questions

What are Intel AI infrastructure plans?

Intel AI infrastructure plans include increased capital spending, expanded semiconductor manufacturing investment, and continued development of advanced chip production technologies to support enterprise AI computing.

Why did Intel increase its capital spending forecast?

Intel increased its capital spending forecast after reporting stronger enterprise demand for data center processors supporting artificial intelligence workloads and additional manufacturing requirements.

What is driving demand for Intel’s data center processors?

Intel said enterprise adoption of AI applications and expanding data center computing requirements have increased demand for processors used alongside AI accelerators.

What is Intel’s 14A manufacturing process?

Intel’s 14A manufacturing process is the company’s next-generation semiconductor fabrication technology that it plans to use for future processors and foundry customers, with high-volume production targeted for 2028.

How does enterprise AI affect demand for data center CPUs?

Enterprise AI deployments require central processing units to manage computing tasks, coordinate workloads, and support applications operating alongside specialized AI accelerators, contributing to increased demand for data center processors.

Federal Aviation Administration Proposal Could Expand Commercial Drone Delivery

Commercial drone delivery providers and major retailers are preparing for broader U.S. operations as proposed Federal Aviation Administration rules aim to simplify drone flights beyond an operator’s visual line of sight. The changes could reduce operational barriers and support expanded last-mile delivery services for businesses and consumers.

Key Takeaways

  • The FAA has proposed rules that would simplify certain commercial drone operations.
  • Drone companies and retailers are preparing to expand U.S. delivery networks.
  • Beyond-visual-line-of-sight operations could reduce deployment costs and improve scalability.
  • Retailers are testing drone delivery for small, time-sensitive consumer orders.
  • Industry participants expect regulatory changes to support broader commercial adoption.

Commercial drone delivery companies, retailers and logistics providers are preparing for broader deployment across the United States following proposed Federal Aviation Administration rules that would simplify flights beyond an operator’s direct visual line of sight. The proposal is significant because current operating requirements have limited the scale of many commercial programs despite growing interest from retailers and technology companies.

The proposed FAA framework would reduce reliance on lengthy waiver processes that operators currently use to conduct beyond-visual-line-of-sight flights. Industry participants have stated that obtaining these approvals can require substantial time and resources, slowing commercial expansion even after successful pilot projects.

The regulatory proposal follows federal efforts to support wider adoption of drone technology for commercial applications. Businesses involved in logistics and autonomous aviation are evaluating how the revised framework could allow larger delivery networks while reducing operational complexity.

What Changes Has the FAA Proposed for Commercial Drone Delivery?

The FAA has proposed rules that would establish a broader pathway for certified operators to conduct commercial drone flights beyond the pilot’s direct visual line of sight. Existing regulations generally require operators to secure individual waivers before conducting these missions.

Beyond-visual-line-of-sight operations

Beyond-visual-line-of-sight operations allow drones to continue flying without a person maintaining continuous visual contact with the aircraft throughout the mission. Commercial operators have identified this capability as an important requirement for expanding delivery networks across larger service areas.

Several drone companies have previously received FAA waivers allowing these operations, but the approval process has varied by project. The proposed rule is intended to provide a more standardized regulatory framework for qualifying operators.

Industry participants have indicated that removing the need for repeated waiver applications could reduce deployment timelines and improve planning for commercial services.

Why Are Companies Expanding Commercial Drone Delivery?

Businesses are evaluating commercial drone delivery as one option for improving last-mile logistics, particularly for lightweight and time-sensitive purchases. Retailers have tested the technology for products such as household essentials, over-the-counter medications, pet supplies and prepared food.

Companies involved in autonomous aviation also view drone delivery as a way to reduce travel distances for certain local deliveries while providing faster fulfillment within defined service areas.

Operational costs and delivery efficiency

Current commercial operations often require additional personnel to comply with existing regulations. Industry executives have stated that broader authorization for beyond-visual-line-of-sight flights could allow fewer operators to supervise multiple aircraft simultaneously, improving operational efficiency.

Businesses are also evaluating drone delivery alongside existing transportation methods rather than as a replacement for traditional vehicle fleets. Weight limits, operating range and weather conditions continue to influence where drones can be deployed effectively.

Retailers have generally concentrated drone operations in suburban communities where delivery distances are relatively short and properties provide suitable landing or drop-off locations. As companies modernize fulfillment strategies, many are also investing in AI-powered inventory systems for retail logistics to improve warehouse coordination and inventory visibility alongside emerging delivery technologies.

How Are Retailers Using Drone Delivery Services?

Several major U.S. retailers have expanded pilot programs and commercial services through partnerships with drone operators. These services are primarily designed for smaller purchases requiring rapid delivery instead of large grocery orders or bulk shipments.

Consumers typically determine eligibility during the online checkout process. Retail systems evaluate whether products meet payload limitations before offering drone delivery as an available fulfillment option.

Retailers have reported expanding the number of participating stores while continuing to test customer demand, delivery performance and operational reliability. Companies have also introduced additional delivery locations as regulatory approvals have increased.

Delivery speed remains one of the primary advantages promoted by operators. Drone services are intended to shorten transportation time for eligible products while reducing dependence on road traffic for nearby deliveries.

Community concerns remain part of the deployment process. Noise, privacy and local acceptance continue to be factors that companies must address as they expand commercial operations.

Which Businesses Are Investing in Commercial Drone Operations?

The commercial drone delivery market includes retailers, logistics providers and specialized aviation companies developing aircraft, flight management systems and operational services.

Retail partnerships with drone operators

Retail companies have established partnerships with drone operators to integrate aerial delivery into existing fulfillment networks. These collaborations allow retailers to test commercial services without building proprietary aviation systems from the ground up.

Specialized drone companies are also working with restaurant chains and food delivery providers to expand service offerings beyond traditional retail deliveries.

Technology developers continue investing in aircraft capable of carrying larger payloads, extending flight range and improving reliability. Battery performance, navigation systems and autonomous flight software remain key areas of development for commercial platforms.

Engineering researchers have noted that continued field deployment contributes to improvements in hardware performance and operational reliability as companies gain additional experience through commercial use. Businesses evaluating autonomous logistics are also monitoring advances in vertiport infrastructure planning, which examines how future aerial transportation networks may support commercial drone operations.

Frequently Asked Questions

What is commercial drone delivery?

Commercial drone delivery is the use of unmanned aircraft to transport eligible products from businesses to customers as part of a retail or logistics operation.

What are beyond-visual-line-of-sight drone operations?

Beyond-visual-line-of-sight operations allow qualified drone operators to conduct flights without maintaining continuous direct visual observation of the aircraft throughout the mission, subject to regulatory approval.

How could the FAA’s proposed rules affect drone delivery?

The proposed rules would establish a broader framework for qualifying commercial operators to conduct beyond-visual-line-of-sight flights, reducing reliance on individual waiver applications.

Which retailers currently offer commercial drone delivery?

Several U.S. retailers have introduced commercial drone delivery through partnerships with specialized drone operators, primarily for small, time-sensitive purchases in selected service areas.

Why are businesses investing in drone delivery technology?

Businesses are evaluating drone delivery as one approach to improving last-mile delivery efficiency, expanding fulfillment options and supporting faster local deliveries for eligible products.

U.S. Venture Capital Hits Record $412.7B as AI Captures 86%

U.S. venture capital firms invested a record $412.7 billion during the first half of 2026, according to PitchBook and the National Venture Capital Association. The report found that most funding was directed toward large AI deals, underscoring the concentration of capital among a small group of companies.

Key Takeaways

  • U.S. venture capital investment reached $412.7 billion in the first half of 2026.
  • PitchBook and the National Venture Capital Association released the midyear findings.
  • AI-related deals accounted for 86% of invested venture capital.
  • Most funding was concentrated in financing rounds valued at $100 million or more.
  • Exit activity remained heavily influenced by a small number of major companies.

The US venture capital investment 2026 market reached a record level during the first six months of the year, with venture firms deploying $412.7 billion, according to the latest midyear report released by PitchBook and the National Venture Capital Association (NVCA). Despite the record total, the report found that funding remained concentrated among a relatively small number of large AI companies and mega-round financings rather than being broadly distributed across the startup ecosystem.

The report showed that the first-half investment total exceeded the previous full-year record for U.S. venture capital activity. While investment volumes climbed sharply, capital allocation remained heavily focused on the largest private technology companies, particularly those developing artificial intelligence models and related infrastructure.

What Did the PitchBook and NVCA Report Reveal?

PitchBook and the NVCA reported that U.S. venture investors deployed $412.7 billion during the first half of 2026, establishing the highest investment total ever recorded for the period.

The report also found that AI venture funding accounted for approximately 86% of all venture dollars invested during the first six months of the year. That concentration reflected continued investor interest in companies building foundation models, AI infrastructure, enterprise AI platforms, and related technologies.

As businesses continue increasing investments in artificial intelligence, finance leaders are also taking a more active role in evaluating technology spending and expected returns, reflecting a growing emphasis on disciplined enterprise AI investment decisions.

Record Investment in the First Half of 2026

Although total investment reached a record level, the report indicated that much of the capital flowed into a limited number of exceptionally large financing rounds.

According to the findings, 91% of invested capital was allocated to venture rounds worth at least $100 million. Smaller financing rounds represented a much smaller share of overall venture investment despite the record-setting totals.

PitchBook Director of U.S. Venture Capital Research Kyle Stanford described the market as divided between companies attracting large-scale investment and those competing for significantly smaller pools of available capital.

The report suggested that headline investment figures alone do not reflect how broadly venture funding is being distributed across startup companies.

How Was Venture Capital Distributed Across Deals?

The concentration of investment was one of the report’s most notable findings.

While venture firms invested hundreds of billions of dollars during the first half of 2026, the overwhelming majority of funding was directed toward companies raising large late-stage financing rounds.

Funding Concentration in Large AI Rounds

According to the report, financing rounds valued at $100 million or more received 91% of deployed capital.

That allocation left comparatively limited funding available for smaller venture-backed companies seeking seed, early-stage, or modest growth financing.

The report did not indicate that venture investment activity had slowed overall. Instead, it showed that available capital increasingly flowed toward companies already capable of raising exceptionally large rounds.

This distribution pattern contributed to record investment totals while limiting the number of startups benefiting from the increased capital deployment.

Why Did AI Companies Receive Most of the Funding?

Artificial intelligence remained the primary destination for venture investment during the first half of 2026.

The report stated that AI-related companies accounted for 86% of all venture dollars invested during the reporting period.

Investors continued allocating substantial capital to businesses developing large language models, AI infrastructure, enterprise software, and other technologies supporting artificial intelligence deployment.

The report did not attribute the concentration to a single company or transaction. Instead, it showed that large AI financings collectively represented the dominant share of venture investment activity.

Corporate buyers are also reviewing AI costs more closely by comparing premium and lower-cost models, demonstrating how investment decisions are becoming increasingly tied to long-term operating expenses rather than technology adoption alone.

Outside AI, venture-backed companies generally attracted a much smaller proportion of total invested capital.

What Did the Report Say About Venture Capital Exits?

The PitchBook and NVCA report also examined liquidity and exit activity during the first half of 2026.

Exit Activity and Market Liquidity

According to the report, total exit value reached approximately $2.2 trillion.

A significant share of that value was associated with a limited number of transactions, particularly those involving SpaceX. The report also identified xAI as another major contributor to overall exit value.

The concentration of exits mirrored the investment data, with relatively few companies accounting for much of the market’s reported liquidity.

PitchBook noted that the exit environment remained centered on large private technology companies rather than reflecting broad participation across venture-backed businesses.

The report also indicated that several anticipated technology IPOs remained closely watched by investors, although it did not present confirmed timelines for future public offerings.

Frequently Asked Questions

How much venture capital was invested in the United States during the first half of 2026?

PitchBook and the National Venture Capital Association reported that U.S. venture capital firms invested a record $412.7 billion during the first half of 2026.

Which organizations published the 2026 U.S. venture capital report?

The report was released by PitchBook and the National Venture Capital Association (NVCA) as their midyear assessment of the U.S. venture capital market.

How much of the funding was directed to AI-related companies?

According to the report, 86% of venture capital invested during the first half of 2026 was directed toward AI-related companies.

Why was venture capital concentrated in large funding rounds?

The report found that 91% of deployed capital went to financing rounds valued at $100 million or more, resulting in most investment being concentrated among a relatively small number of companies.

AI Data Center Electricity Costs Rise for Manufacturers Across PJM

Manufacturers across the PJM Interconnection region are facing higher electricity costs as expanding AI data centers increase demand on the power grid. Rising capacity charges are adding to operating expenses for factories, prompting some businesses to adjust pricing, production schedules, and energy strategies.

Key Takeaways

  • AI data center growth is contributing to higher electricity demand across the PJM grid.
  • Manufacturers report significant increases in capacity charges and overall power costs.
  • Higher energy expenses are affecting factory operating costs and business planning.
  • Some manufacturers are evaluating onsite generation and production schedule changes.
  • Policymakers and regulators are reviewing proposals related to large electricity users.

Manufacturers operating across the PJM Interconnection region are reporting higher AI data center electricity costs as expanding computing facilities increase demand for power generation capacity. The higher demand has contributed to rising capacity charges, adding to electricity expenses for factories throughout parts of the Midwest and Mid-Atlantic and influencing business decisions related to pricing, production, and energy management.

The issue is affecting industrial businesses located within PJM Interconnection’s service territory, which spans 13 states and the District of Columbia. The regional transmission organization manages the movement of wholesale electricity across one of the country’s largest power markets, where electricity demand has increased as companies build new data centers to support artificial intelligence services. Businesses tracking developments in AI infrastructure may also find context in this analysis of data center demand forecasts.

One example is Ohio-based Belden Brick Company, which reported a sharp increase in monthly capacity charges over the past year. Company officials said the higher electricity costs have reduced profit margins despite price adjustments for its products.

What Happened to Factory Electricity Costs?

Manufacturers in several Rust Belt states have reported notable increases in electricity expenses tied primarily to capacity charges rather than overall energy consumption. Capacity charges are designed to ensure that sufficient electricity generation remains available during periods of peak demand.

Within the PJM market, capacity prices have risen substantially over the past two years. The increase has been attributed to limited growth in electricity generation alongside rapidly expanding demand from large-scale data centers.

Industrial customers often bear a larger share of these charges because of their significant electricity usage. For manufacturers operating energy-intensive facilities, even modest increases in electricity prices can have measurable effects on operating costs.

How Have Capacity Charges Changed?

PJM’s capacity market establishes prices paid to power generators for maintaining available generating capacity. Those costs are passed through to electricity customers by utilities.

Recent PJM capacity auction results showed prices increasing by more than 1,000% compared with earlier auction periods. The higher prices have translated into larger monthly charges for many industrial customers throughout the region.

For some manufacturers, capacity charges represent a significant portion of electricity bills. Businesses that rely on continuous production processes may have limited flexibility to reduce consumption during periods of peak demand, making these costs difficult to avoid.

Manufacturers have reported that electricity has become a larger component of operating expenses, requiring closer evaluation of production planning and energy management strategies.

Why Are AI Data Centers Increasing Power Demand?

Artificial intelligence applications require extensive computing infrastructure supported by large data centers operating around the clock. These facilities consume substantial amounts of electricity to power servers while also supporting cooling systems that maintain operating temperatures.

Several states served by PJM have become attractive locations for new data center development because of existing telecommunications infrastructure, available land, and proximity to major population centers.

The addition of multiple large facilities has increased electricity demand faster than new power generation has entered the market. PJM officials have stated that data centers can be constructed more quickly than generating facilities needed to support them, contributing to tighter supply conditions.

During periods of high electricity usage, sufficient generation capacity must remain available to maintain grid reliability. Capacity markets are intended to encourage investment in additional generation while compensating existing suppliers for maintaining reserve capacity.

PJM also implemented emergency measures during a recent period of extreme heat after electricity demand reached a record level within its service territory. Grid operators requested some customers reduce electricity consumption to help maintain system reliability.

How Are Manufacturers Responding to Higher Energy Bills?

Manufacturers are evaluating several approaches to manage higher electricity expenses while maintaining production schedules.

Some companies have adjusted product prices to offset rising operating costs. Others are examining investments in onsite electricity generation that could reduce dependence on the regional power grid during certain operating periods.

Manufacturers are also reviewing production schedules to determine whether some operations can be shifted to hours when electricity prices are lower. Facilities with flexible manufacturing processes may be able to reduce overall electricity costs by adjusting production timing.

What Operational Changes Are Companies Considering?

Industrial companies have also increased attention on energy efficiency projects that reduce electricity consumption without affecting production output.

Some manufacturers are evaluating combined heat and power systems or direct natural gas supply for certain operations where technically feasible. Others continue assessing equipment upgrades that improve energy efficiency across manufacturing facilities.

Business leaders have also indicated that rising electricity expenses are influencing long-term investment decisions, particularly for facilities operating with relatively narrow profit margins. Companies monitoring regulatory developments around artificial intelligence can also reference U.S. AI incident reporting legislation as policymakers continue evaluating the technology’s broader impact.

Industry organizations representing manufacturers have expressed concern that continued increases in electricity costs could affect competitiveness for domestic production facilities.

What Role Does PJM Play in Electricity Pricing?

PJM Interconnection operates the wholesale electricity market serving portions of the Midwest and Mid-Atlantic. Its responsibilities include coordinating electricity transmission, balancing supply and demand, and administering capacity auctions.

Capacity auctions establish payments for electricity generators willing to maintain available generating resources for future periods of expected demand. Those payments are intended to ensure that adequate generating capacity remains available to maintain grid reliability.

Utilities purchasing electricity through the PJM market recover many of those costs through customer rates. Industrial customers frequently experience larger financial impacts because of higher electricity consumption compared with residential customers.

The combination of growing electricity demand and slower additions of new generating resources has contributed to higher capacity market prices across the PJM region.

Frequently Asked Questions

Why are AI data centers increasing electricity costs for manufacturers?

Large AI data centers require significant amounts of electricity, increasing demand for available generation capacity. Higher demand has contributed to rising capacity charges within the PJM electricity market, affecting industrial customers.

What are capacity charges on industrial electricity bills?

Capacity charges are fees that help compensate electricity generators for maintaining enough available power to meet peak demand and support grid reliability.

What is PJM Interconnection and how does it affect electricity prices?

PJM Interconnection is a regional transmission organization that operates wholesale electricity markets across 13 states and the District of Columbia. Its capacity market influences electricity costs paid by utilities and large customers.

How are manufacturers responding to rising energy costs?

Manufacturers are reviewing pricing strategies, evaluating onsite power generation, improving energy efficiency, and adjusting production schedules where possible to manage higher electricity expenses.

Could new electricity regulations affect industrial businesses?

Yes. Federal and state regulators are reviewing proposals related to electricity demand from large users, and manufacturing organizations are participating in discussions about how future regulations could affect industrial electricity costs.

AI Adoption Shows Mixed Impact on Hiring Across Organizations

New workforce data from Ramp and Revelio Labs suggests AI adoption is not producing one uniform hiring pattern. Companies making sustained, higher-intensity AI investments recorded stronger headcount growth, including entry-level gains, while lower-intensity adopters saw less measurable hiring benefit and researchers cautioned against treating the findings as proof that AI broadly creates jobs.

Key Takeaways

  • Ramp and Revelio Labs analyzed AI spending and workforce data from more than 21,000 U.S. companies.
  • High-intensity AI adopters recorded a 10.2% increase in headcount over the two years after adoption.
  • Entry-level headcount rose 12% among high-intensity adopters.
  • Researchers cautioned that the findings do not prove AI adoption directly creates jobs across all organizations.

What Did The Ramp And Revelio Labs Data Show?

A Broad Workforce Analysis

Ramp and Revelio Labs released workforce findings on June 30, 2026, showing that companies making deeper AI investments tended to expand headcount faster than comparable organizations that had not yet adopted AI. The analysis linked Ramp transaction data on AI vendor spending with Revelio Labs workforce records covering more than 21,000 U.S. companies.

The report found that high-intensity AI adopters maintained employment levels roughly 10.2% higher than companies that had not yet adopted AI. Ramp defined high-intensity adopters as companies in the top third of AI spending per employee during the first three months after adoption, at about $30 per employee per month.

The findings add detail to the broader discussion around AI adoption and workforce planning. They suggest that AI spending may coincide with hiring growth in some organizations, but only when companies move beyond limited experimentation.

Stronger Spending, Stronger Signals

Ramp and Revelio Labs found that hiring gains were concentrated among companies making larger and more sustained AI investments. Low-intensity adopters, including companies making smaller AI purchases or limited pilot investments, did not show statistically significant employment gains.

The report also noted that employment gains did not appear immediately. Ramp stated that headcount effects tended to emerge after a six- to 12-month learning period, suggesting that companies may need time to integrate AI tools into workflows before any hiring impact becomes visible.

That distinction matters as organizations continue reassessing AI spending priorities while balancing software costs, productivity goals, and long-term hiring plans.

What Happened To Entry-Level Hiring?

Junior Roles Did Not Follow One Pattern

Ramp and Revelio Labs also examined entry-level employment, a major concern in the AI labor market debate. Among high-intensity AI adopters, entry-level headcount increased 12% over the two years after adoption.

Revelio Labs reported that the share of entry-level workers increased by 1.15 percentage points among high-intensity adopters compared with companies that had not yet adopted AI. Low-intensity adopters moved in the opposite direction, with a modest decline in entry-level workforce share.

The results differ from other labor market research that has linked AI to weaker demand for younger or less-experienced workers. Goldman Sachs economists estimated in April 2026 that AI reduced U.S. monthly payroll growth by roughly 16,000 jobs over the previous year, with negative effects falling largely on younger, less-experienced workers.

Growth May Have Started Earlier

Ramp and Revelio Labs cautioned that the findings should not be read as proof that AI adoption automatically creates jobs. Revelio Labs stated that AI adopters were already different from non-adopters before adoption. They tended to be larger, faster-growing, more engineering-intensive, more likely to be venture-backed, and concentrated in technology-adjacent sectors.

That context is important. Companies that were already growing may have had more resources to invest in AI, hire workers, and expand operations at the same time.

The report states that the findings “do not imply that AI mechanically creates jobs.” Instead, they show that the companies making the deepest and most sustained AI investments are also the companies experiencing stronger workforce growth.

Which Business Conditions May Affect Hiring Outcomes?

Capacity To Implement AI

Ramp and Revelio Labs identified several possible reasons why some companies may see hiring growth after AI adoption while others do not. Businesses with stronger capital access, technical expertise, experienced management, and implementation capacity may be better positioned to turn AI investment into operational expansion.

Productivity And Expansion

The report pointed to knowledge-based tasks such as software development, debugging, technical documentation, internal tools, research, and analysis as areas where AI may reduce production costs. If those savings allow a company to launch more products, serve more customers, or expand into new markets, hiring demand may increase across departments.

For companies scaling operations across locations, workforce planning can also involve compliance, payroll, and employment-law considerations. Those issues are especially relevant in multi-state hiring challenges as companies expand teams beyond one jurisdiction.

What Could Shape Future Workforce Growth?

Ramp and Revelio Labs suggested that the long-term employment effects of AI adoption may depend on whether companies can move from tool purchases to sustained implementation. Companies with stronger resources may have more ability to train employees, redesign workflows, and apply AI to core business operations.

Organizations without those resources may remain in limited experimentation. That could widen performance gaps between companies that integrate AI into daily operations and those that do not.

The report does not settle the broader AI jobs debate. It shows a more mixed pattern: some higher-intensity AI adopters are hiring more, including at the entry level, while other companies show weaker or less measurable hiring outcomes.

Frequently Asked Questions:

What did the Ramp and Revelio Labs report examine?
The report examined AI spending data from Ramp and workforce records from Revelio Labs. It covered more than 21,000 U.S. companies and evaluated how employment changed around AI adoption.

What is a high-intensity AI adopter?
A high-intensity AI adopter is a company in the top third of AI spending per employee during the first three months after adoption. Ramp described that level as about $30 per employee per month.

Did the report conclude that AI creates jobs?
No. The report found that high-intensity AI adopters experienced stronger workforce growth, but researchers cautioned that the data does not prove AI adoption directly or universally creates jobs.